Mediobanca: the gap between Gdo and discount retailers narrows. Do lively
Mediobanca: the gap between Gdo and discount retailers narrows. Do lively
- Information
For 2025 Mediobanca’s Research Department estimates, in its annual sector focus, growth in Italian Gdo sales of 4,3 per cent.
With virtually no inflation, the figure far exceeded the +2,3% of 2024.
In 2024, the aggregate of the main national food-focused groups generated net turnover (excluding VAT) of 109,8 billion, of which 13,4 billion was attributable to foreign-controlled operators (12,2% of the total).
Between 2019 and 2024, sales increased by 30,9%, with a compound annual growth rate (CAGR) of 5,5%.
Discount retailers still lead on margins
In 2024, it was observed that discount retailers were no longer proving so uncatchable: average turnover across the various brands increased by 3,6% on 2023, compared with +2% for the other operators, recording an average sales growth rate—between 2019 and 2024—of 8,4% (+4,9% for the other channels).
Profitability stands out: discounters’ EBIT stood at 2024 in 5,1%, ahead of the 2,1% recorded by competitors, while ROI stood at 16,6% (5,6% for the other operators).
Some interesting points from the accounts
Examining the various brands closely reveals many peculiarities.
Coop Radenza achieved the highest turnover growth between 2019 and 2024: +13,5% per year on average, followed by In’s Mercato (+12,1%), Tatò Paride (+10,4%) and Agorà (+10,1%).
Restricting the analysis to the last year alone, the leaders were RetailPro (+7,9%), Agorà (+7,8%) and Radenza (+6,3%), followed by the Trentino cooperative Sait (+5,4%), Eurospin (+5,1%), Selex (+4,6%), Conad and Lidl (both +3,9%).
Moreover, higher EBIT levels of 2024 distinguish Noto (which controls AZ) with 6,5%, the discount retailers Cive (6,1%) and Eurospin (5,9%). Immediately after them come Agorà (5,2%) and Lidl (5%).
The ranking by return on invested capital (ROI) places Radenza Group on the podium, with 20,6%, followed by Md at 19,6% and Eurospin (18,3%), closely followed by Eurospin affiliate Cive (16%) and In’s Mercato (15,6%).
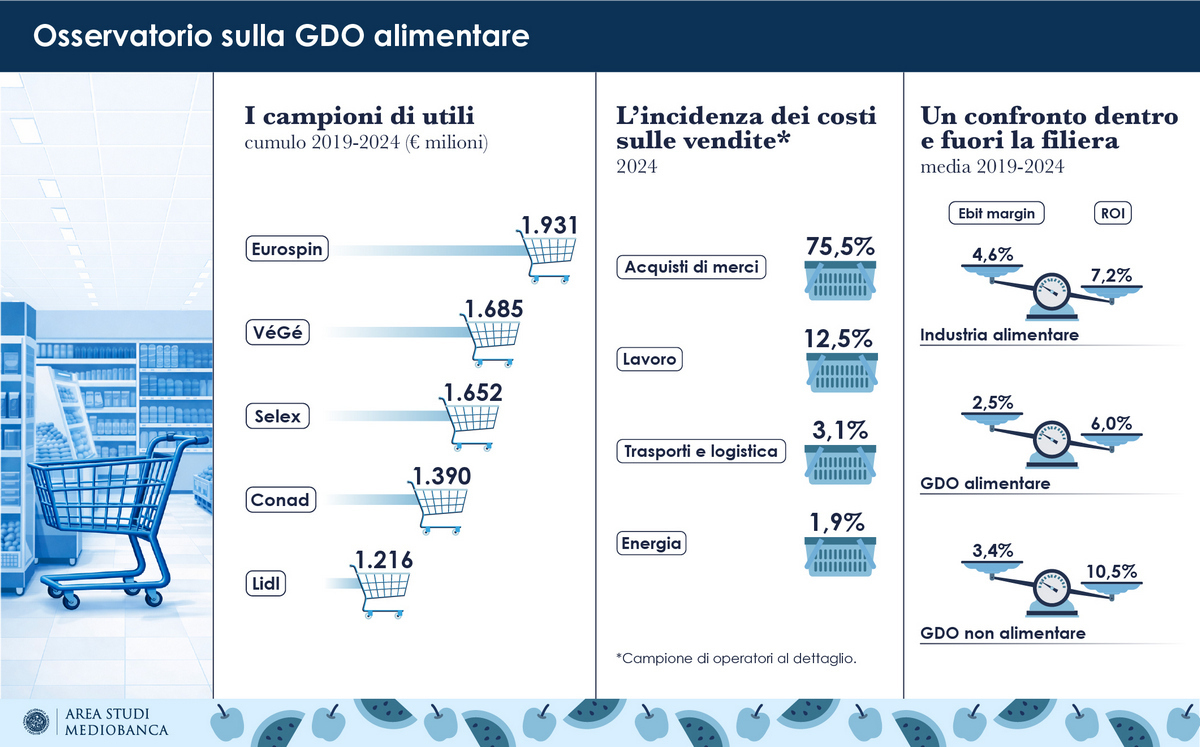
Eurospin ranks first for cumulative profits between 2019 and 2024: with 1.931,2 million, it surpasses VéGé, at 1.685 million, and Selex (1.651,5 million).
Pac 2000 A (Conad) is, according to Mediobanca, Italy’s largest cooperative, with sales of 2024 amounting to 4.902 million, followed by Coop Alleanza 3.0, at 3.975 million, and Conad Nord Ovest, at 3.239 million, which in turn precedes Unicoop Firenze, at 3.045 million.
Organised distribution on the move
The market share of the seven leading national Do operators rose from 52,2% in 2010 to 71% in October 2025.
Between 2019 and 2025, this group’s market share, excluding Conad and Coop, grew by 7,1 points, also thanks to the increase in its membership base.
VéGé is the operator that attracted the largest number of new members (seven), two of whom were already members of other organisations (D.IT and C3).
In 2024, Agorà stands out, thanks to its profitability—the highest in the sector, with an EBIT margin of 5,2% and ROI of 14,3%—and its rising sales, from 2019, at an average annual rate of 10,1 per cent.
The average annual growth rate of 6,6%—between 2019 and 2024—is also exceeded by Selex (+7,3%), with EBIT of 3,3% and ROI of 10,3 per cent.
C3 achieves a ratio of net operating margin to turnover of 3,9%, higher than the average (3,1%), but remains behind in terms of return on investment (8%).
In 2024, the figures for VéGé (EBIT margin 2,9% and ROI 9,2%) were instead below the segment average, with turnover growing by 5,5% per year on average since 2019.
At the bottom, again in terms of EBIT, are Crai and Despar (respectively 0,9% and 1,2%); the latter also ranks last for ROI (4,3%).
There are twenty-six organised distribution companies with turnover exceeding 500 million.
The largest turnover increase 2024 was achieved by Multicedi (+13,2% on 2023) and FG Holding (Magazzini Gabrielli, +12,8%), followed by Megaholding (Megamark, +12,6%), Retail Evolution (Iperal, +10,8%) and Abbi Holding (+10,7%).
Retail Evolution is the leading operator by EBIT margin (7,6%), ahead of Verofin (Tigros) (7,1%) and F.lli Lando (5,7%).
Gruppo Rossetto has the best return on invested capital (20,8%), closely followed by Unicomm and Tigros (both at 19,7%).
Other articles:
How many discount retailers are there in Italy?
This article was translated from the original Italian version with the assistance of artificial intelligence. In case of discrepancies, please refer to the original Italian version.