


Mineral waters between new formats and sustainability in packaging
Mineral waters between new formats and sustainability in packaging
- Information
Dynamic and in good health, the sector is focusing on innovation in formats and sustainability in packaging, highlighting the products’ chemical and physical properties.
 In the year ending in December 2025, the Italian mineral water market showed positive and lively growth. Overall, more than 11,9 billion litres of product were sold, marking a 2,8% year-on-year increase in volume. Total turnover reached almost 2,9 billion euros, up 4,4%, driven both by increased consumption and inflationary dynamics (Circana data, Total Italy, Hypermarkets+Supermarkets+Lsp+Discounts).
Geographical areas and distribution channels
The geographical distribution of sales by volume highlights the highest concentration in Southern Italy, with a share of 32% and 28,1% of value. This is followed by the North-West, which accounts for 26,2% by volume and 27,9% by value. Central Italy+Sardinia represents 24,6% of volume and 25,7% of value, while the North-East closes with a share of 17,2% by volume and 18,3% of turnover. As regards distribution channels, supermarkets confirm their central role, accounting for 50,7% of volume and 55,9% of total value. Discount stores rank as the second key channel, with a share of 31,7% by volume and 23,6% by value. Free-service outlets, on the other hand, account for 9,8% of volume and 11,9% of value, while hypermarkets account for 7,8% by volume and 8,5% by value.
Segment performance
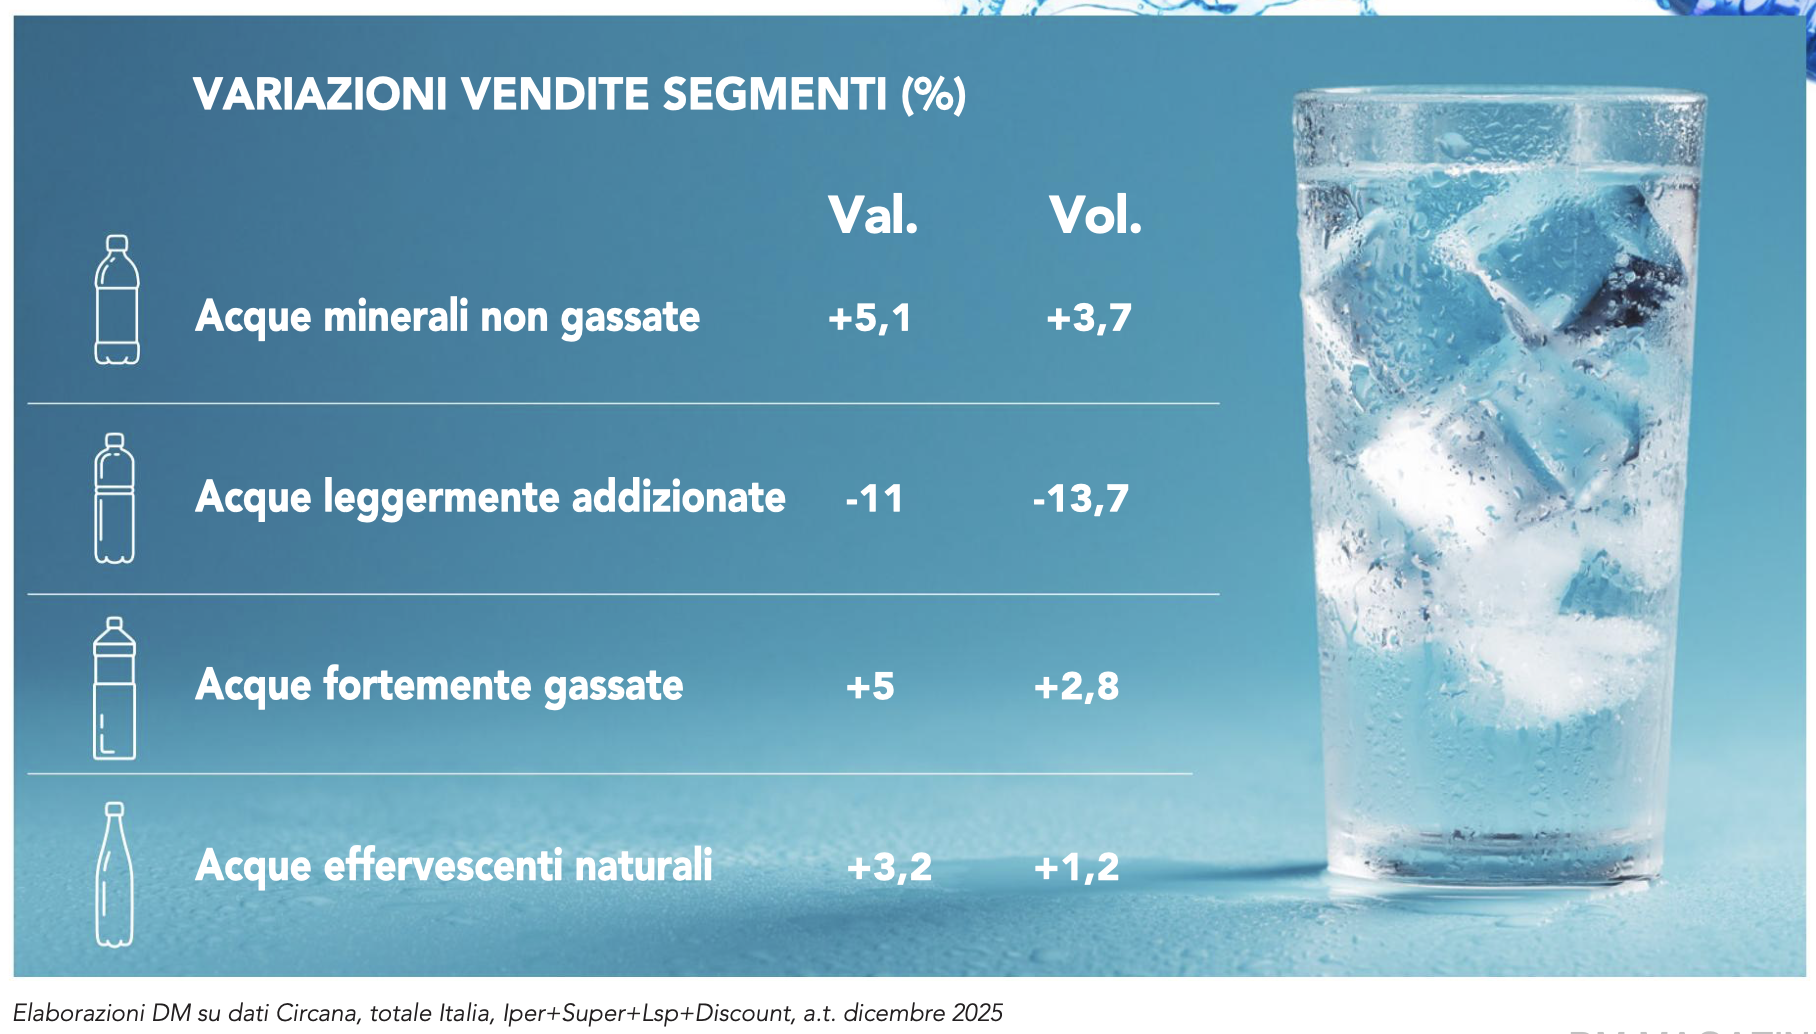
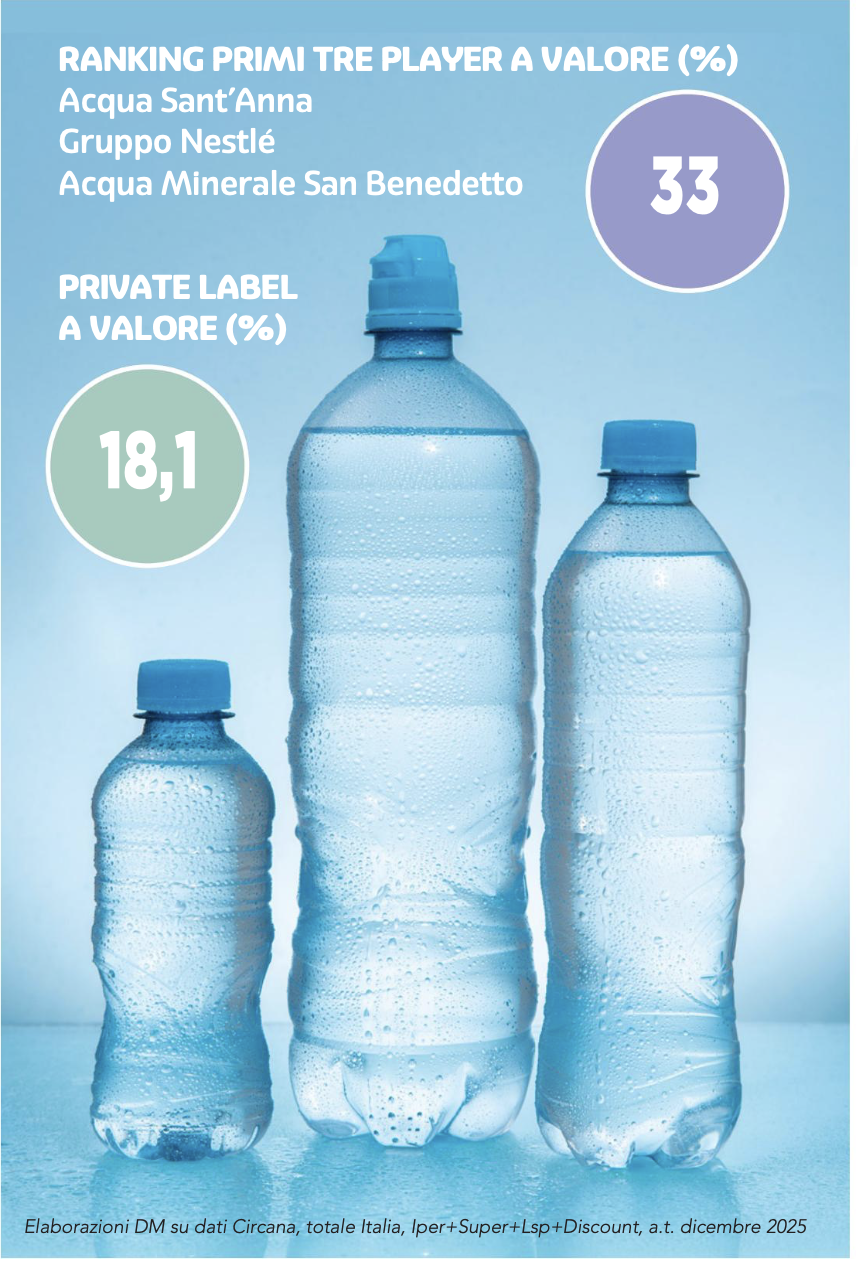 Within the market, the different segments show differing dynamics. Still mineral water represents the largest share both in absolute terms and in terms of annual performance, with more than 9 billion litres sold and turnover of just over 2 billion euros, increasing by 3,7% in volume and 5,1% in value. Following in terms of growth, but well behind in terms of market share, are highly carbonated waters, which, with 1,27 billion litres and almost 350 million in turnover, show good performance, with an increase of 2,8% by volume and 5% by value. Naturally sparkling waters are also growing, albeit more moderately (+1,2% by volume and +3,2% by value), reaching 1,3 billion litres and 380 million in turnover. Conversely, the slightly added waters segment is recording a sharp overall decline, with -13,7% in volume and -11% in value, reaching 322,6 million litres and more than 71 million in turnover. The competitive landscape is characterised by the predominance of branded manufacturers, with the top three players – Acqua Sant'Anna, Gruppo Nestlé, Acqua Minerale San Benedetto – collectively accounting for 33% of the market by value. Private label nevertheless holds an important position, with 18,1%.
Read more about DM Magazine February 2026
This article was translated from the original Italian version with the assistance of artificial intelligence. In case of discrepancies, please refer to the original Italian version.
