


Home care cleaning: the focus is on researching innovative and practical solutions
Home care cleaning: the focus is on researching innovative and practical solutions
- Information
In a rich and diverse sector, companies are increasingly active in responding to consumers' needs with innovative solutions that can meet specific requirements and are quick to use.
 Unlike what happened during 2024, in the year ending 28 December 2025, the home care cleaning market showed a stable situation, recording turnover of almost 1,7 billion euros (-0,03%) with more than 723 million units sold (-0,8%). “While promotions and assortment played a crucial and supportive role in 2024,” comments Elena Pezzotti of NIQ, “with the close of last year their strength declined, affecting category performance. In fact, the change in promotional intensity per pack recorded +0,8 points in 2024 and +0,2 points in 2025; meanwhile, the change in the average number of references per point of sale recorded +1,8% in 2024 and +0,5% in 2025” (NIQ data, total Italy, Hypermarkets+Supermarkets+Free-service stores+Discount stores+Drug specialists).
Geographical areas and distribution channels
The geographical area that contributed most to category dynamics is 16,6%, which, with the highest sales location per 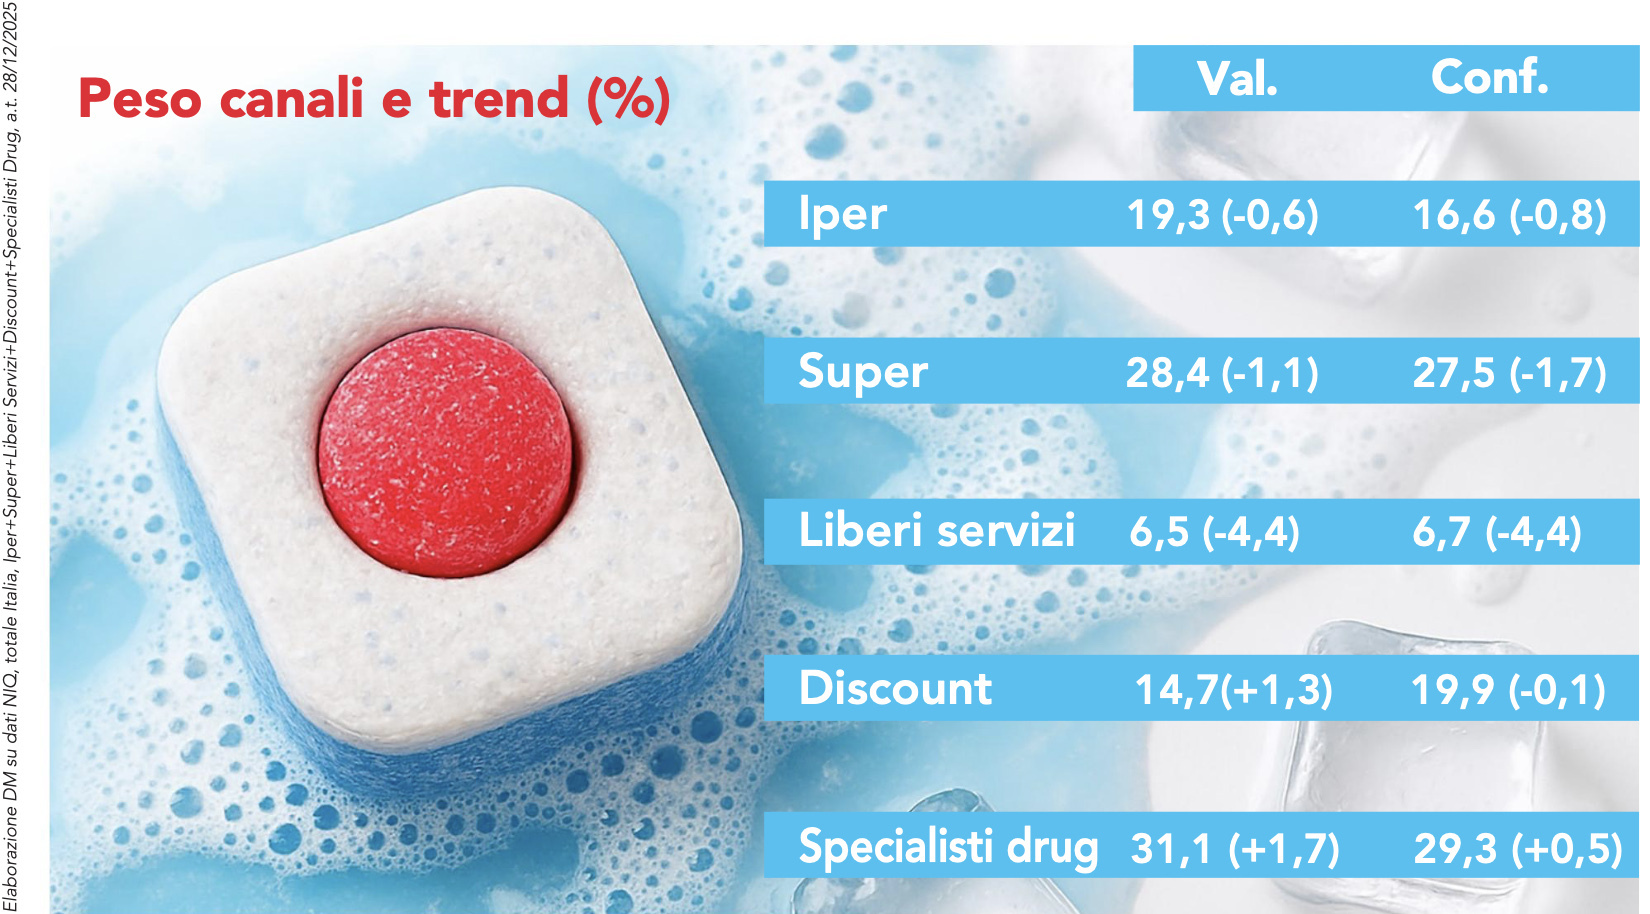 pack (-0,8%), recorded growth in sales by value (6,7%), but not by unit (-0,2%). Second in the ranking, with a sales location of 27,3%, is Area 1, which shows more pronounced trends, with a decline both by value and by unit (-0,6% by value and -1% by pack). Third in the ranking is Area 3 (24,5%), also with a negative trend (-0,4% by value and -1,4% by pack). Finally, Area 2, with a sales location per pack of 20,2%, recorded value growth of 0,8%, while units sold declined (-0,6%). Among the channels, drug specialists rank first for sales location per pack (29,3%), with growth not only in turnover (+1,7%), but also in packs sold (+0,5%). The silver medal goes to supermarkets (27,5%). In this case, however, performance was negative (-1,1% by value and -1,7% by pack). Discount stores account for 19,9% of unit sales, with value growth (+1,3%) and stable unit sales (-0,1%). Hypermarkets follow, with the same sales location and negative trends (-0,6% by value and by pack). The decline of free-service stores continues: with a sales location per pack matching the figure already given, they also recorded a decrease in sales this year (-4,4% by value and -4,4% by pack).
Segment performance
By contribution in units, the market under review comprises the following segments: surface cleaners (60,3%) and dishwashing detergents (39,7%). “Accounting for more than half of sales,” Elena Pezzotti continues, “the surface cleaners segment, which records negative trends by value (-0,3%) and by unit (-0,6%), has a predominant influence on market dynamics. As regards the main proposition, small surfaces (share by pack 25%) show trends that are broadly in line with the segment total (+0,3% by value and -0,9% by pack). Conversely, products for toilet care (share by pack 12%) record positive trends regardless of the unit of measurement (+0,6% by value and +1,2% by pack): this is due to promotional growth (promotional intensity per pack 30,4%, +0,6 points) and assortment growth (1 3,1 references, +1,4%). Floor cleaners—in third place for contribution in units (10,3%)—instead show negative performance (-1,8% by value and -0,9% by pack). In this case, the decline in promotional activity (promotional intensity per pack 34,1%, -3,4 points) is such that it negatively affects the subsegment's performance.” The dishwashing detergents segment, supported by an increase in the average price (2,56 euros, +1,4%), records growth by value (+0,3%) offset by a decline in units (-1%). In this context, dishwasher detergents (+3,2% by value and +0,5% by pack) and related additives (+4% by value and +3,2% by pack) saw sales increase compared with last year thanks to the boost from assortment (change in the average number of references per point of sale +1,2% for detergents and +1,8% for additives). Conversely, hand dishwashing detergents show negative performance (-4,3% by value and -3% by pack).
Read more about DM Magazine February 2026
This article was translated from the original Italian version with the assistance of artificial intelligence. In case of discrepancies, please refer to the original Italian version.
