


Premium supply chains are being enhanced in tomato-based products
Premium supply chains are being enhanced in tomato-based products
- Information
The market is showing substantial resilience in consumption, but players' strategies are decisively shifting towards certified origin, sustainability and process innovation to counter the decline in average prices.
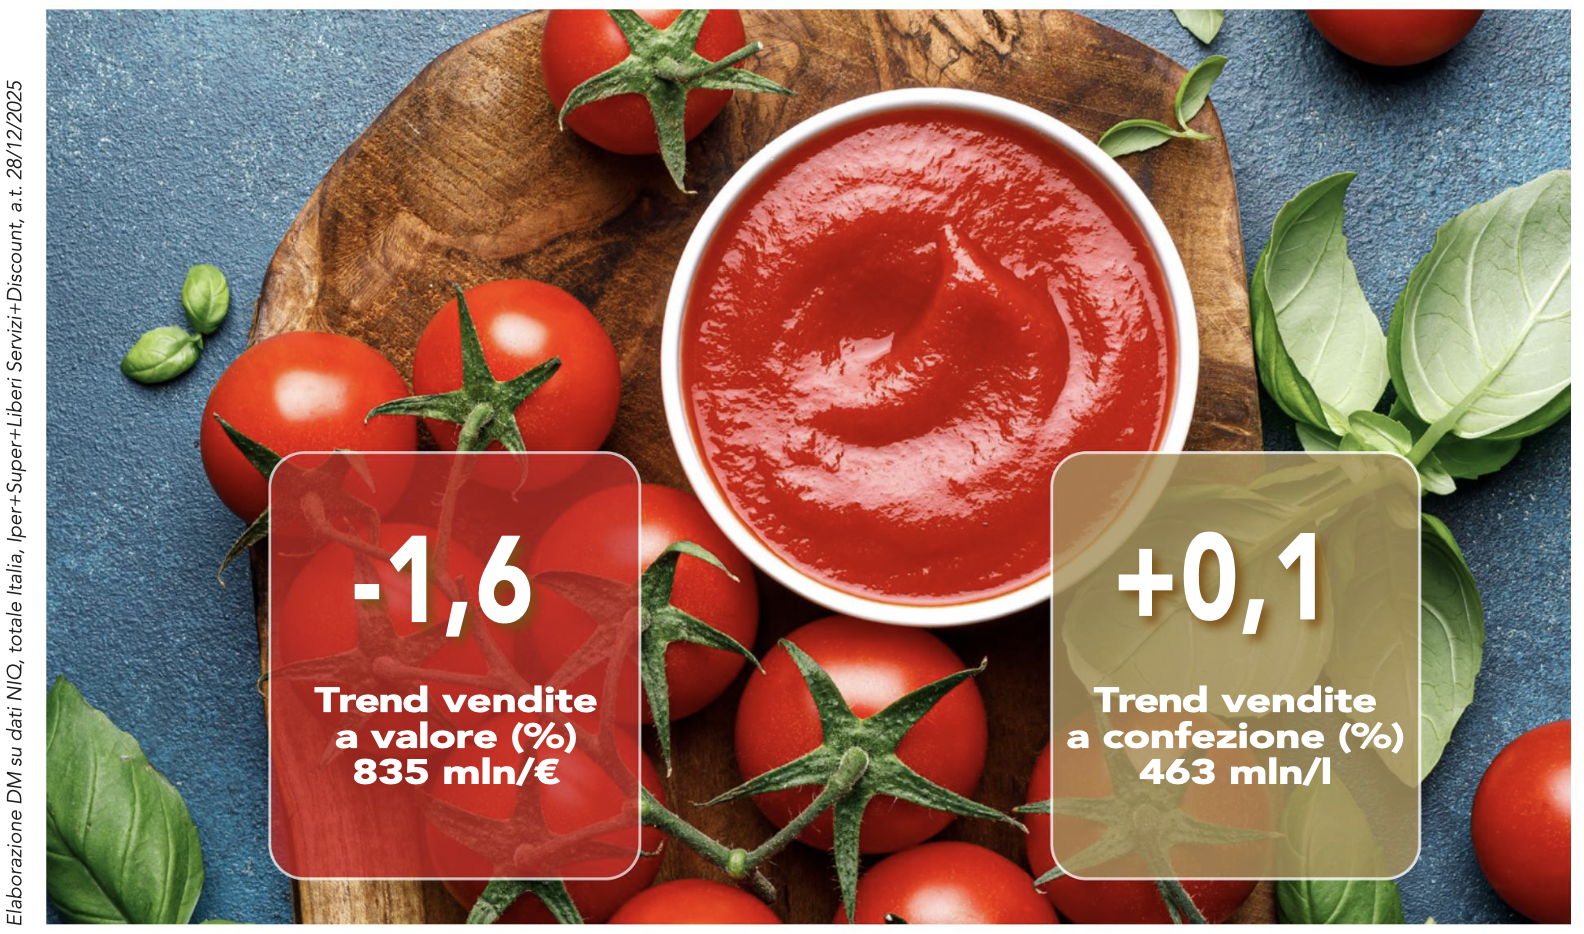 The tomato-based products market in Italy achieved a turnover of almost 835 million euros in the year ending 28 December 2025, recording a decline in turnover of 1,6%. The decline in value was accompanied by virtually flat trends in volume (+0,1%) and packs (-0,4%), for a total of 463 million litres and 728 million units sold. “In this context,” says Elena Pezzotti of NIQ, “the decline in the average price per litre (1,80€; -1,6%) had a negative impact on value performance. Promotional intensity remains substantially stable at 39,6% in volume (+0,4%), while the average assortment is 43,4 SKUs and records growth of 1,6% (NIQ data, total Italy, Hypermarkets+Supermarkets+Free-service stores+Discount stores).”
Geographical areas and distribution channels
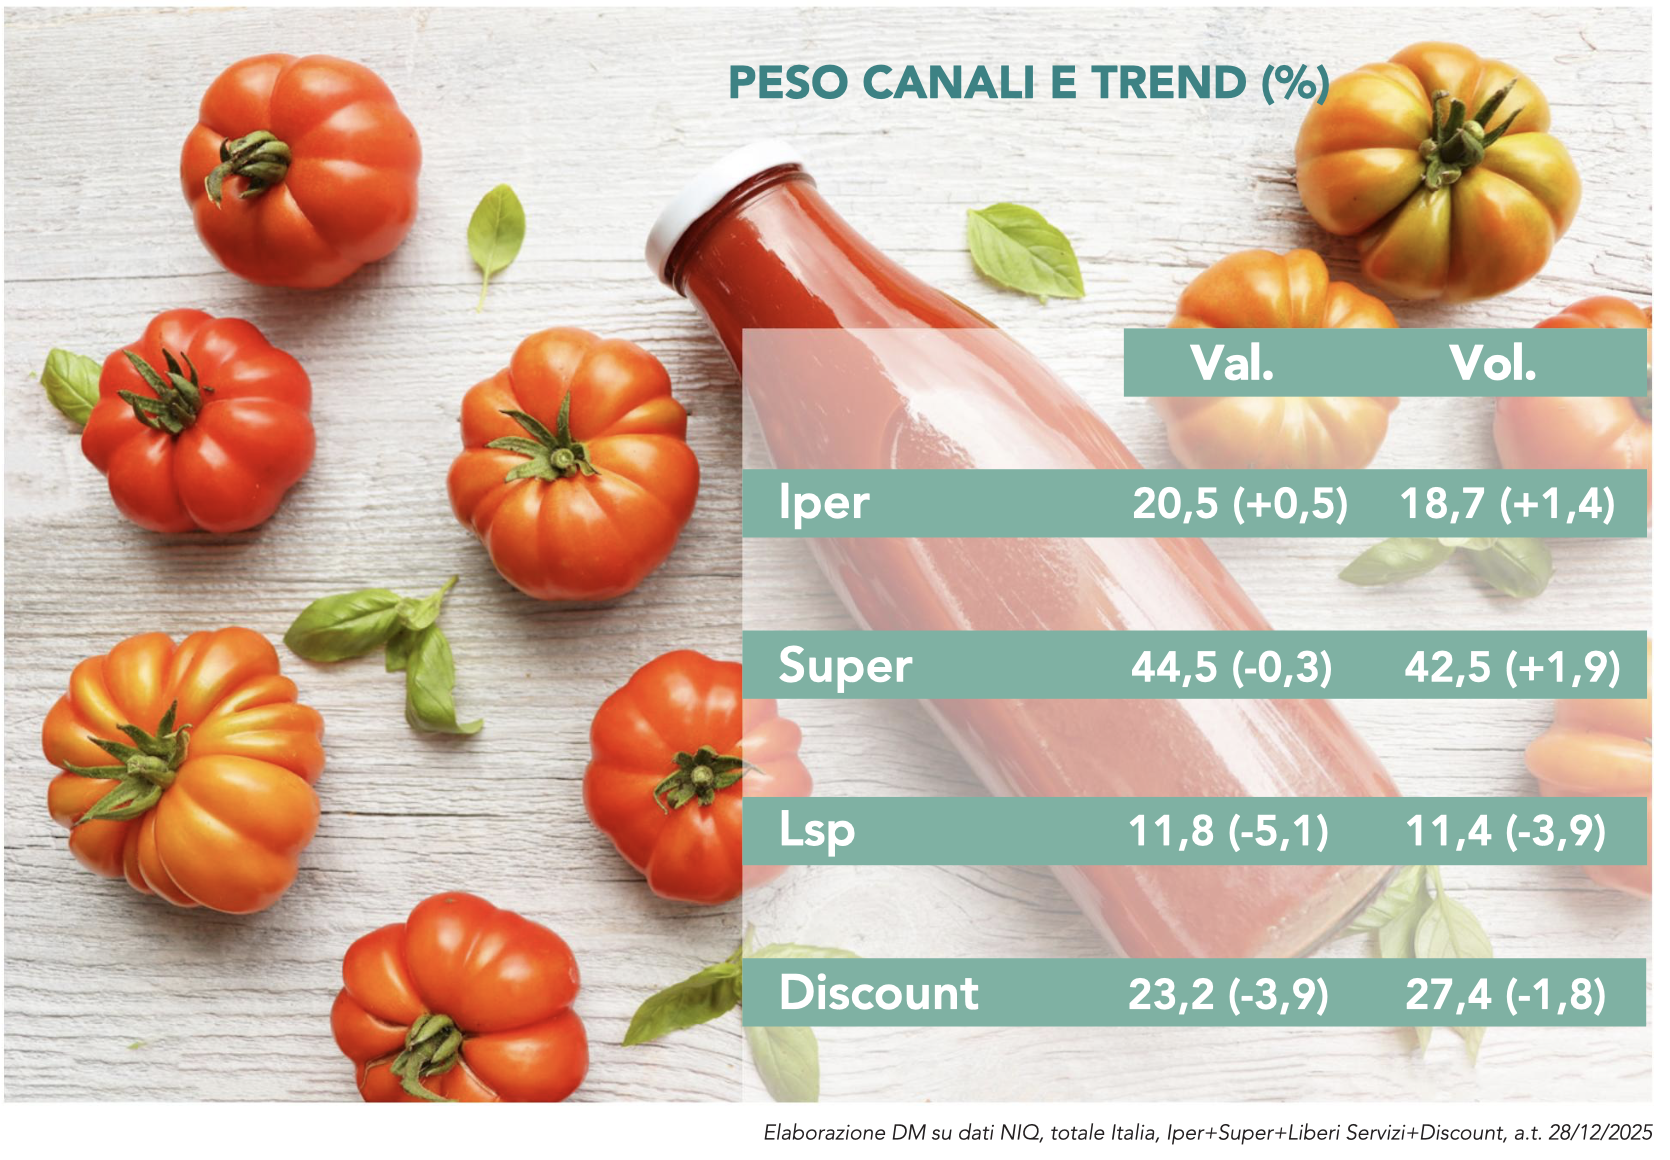 The macro-trends identified for Italy as a whole are also reflected at geographical-area level, with Area -2,8% having had the greatest impact on category dynamics: with the largest sales location by volume (18,7%), it recorded a decline in sales by value (0,5%), volume (1,4%) and units. Ranking second, with a sales location by volume of 1,2%, Area 3 shows a decline in value of 1,7%, but sees a slight increase in volumes (+0,7%) and packs (+0,05%). Third in the ranking is Area 1, with a share of sales by volume of 22,4%, recording exclusively negative trends: -1,9% by value, -0,5% by volume and -1,2% by packs. Finally, Area 2, with a lower sales location by volume of 13,9%, shows variations in sales of -0,7% by value, +0,5% by volume and -0,5% by packs. “Among the channels,” Pezzotti continues, “supermarkets rank first for sales location by volume (42,5%), recording a slight decline in turnover (-0,3%), offset by opposite growth in volumes and packs (+1,9% and +1,8%). The silver medal for market share goes to discount stores (27,4%), a channel distinguished, however, by negative performance (-3,9% in value, - 1,8% in volume and in packs). Hypermarkets contribute a share of sales by volume, with growth trends in value, volume and units. Free-service stores, with a sales location by volume of 11,4%, record the weakest performance: -5,1% in value, -3,9% in volume and -4,1% in packs.”
Segment performance
The tomato-based products market, by contribution to volume, consists of the following segments: tomato passata (65,6%), tomato pulp (19,4%), peeled tomatoes and cherry tomatoes (13,5%) and tomato purées (1,5%). “The tomato passata segment, accounting for more than half of sales, has a predominant influence on market dynamics and records positive trends in value (+1,2%), volume (+3%) and units (+1,9%),” explains Elena Pezzotti. “These results are underpinned by promotional activity of 44,5% (+1,4%) and assortment activity (15,7 SKUs; +3%). The main proposition of bottled/jarred tomato passata (volume share 58,6%) certainly played a crucial role, recording positive trends 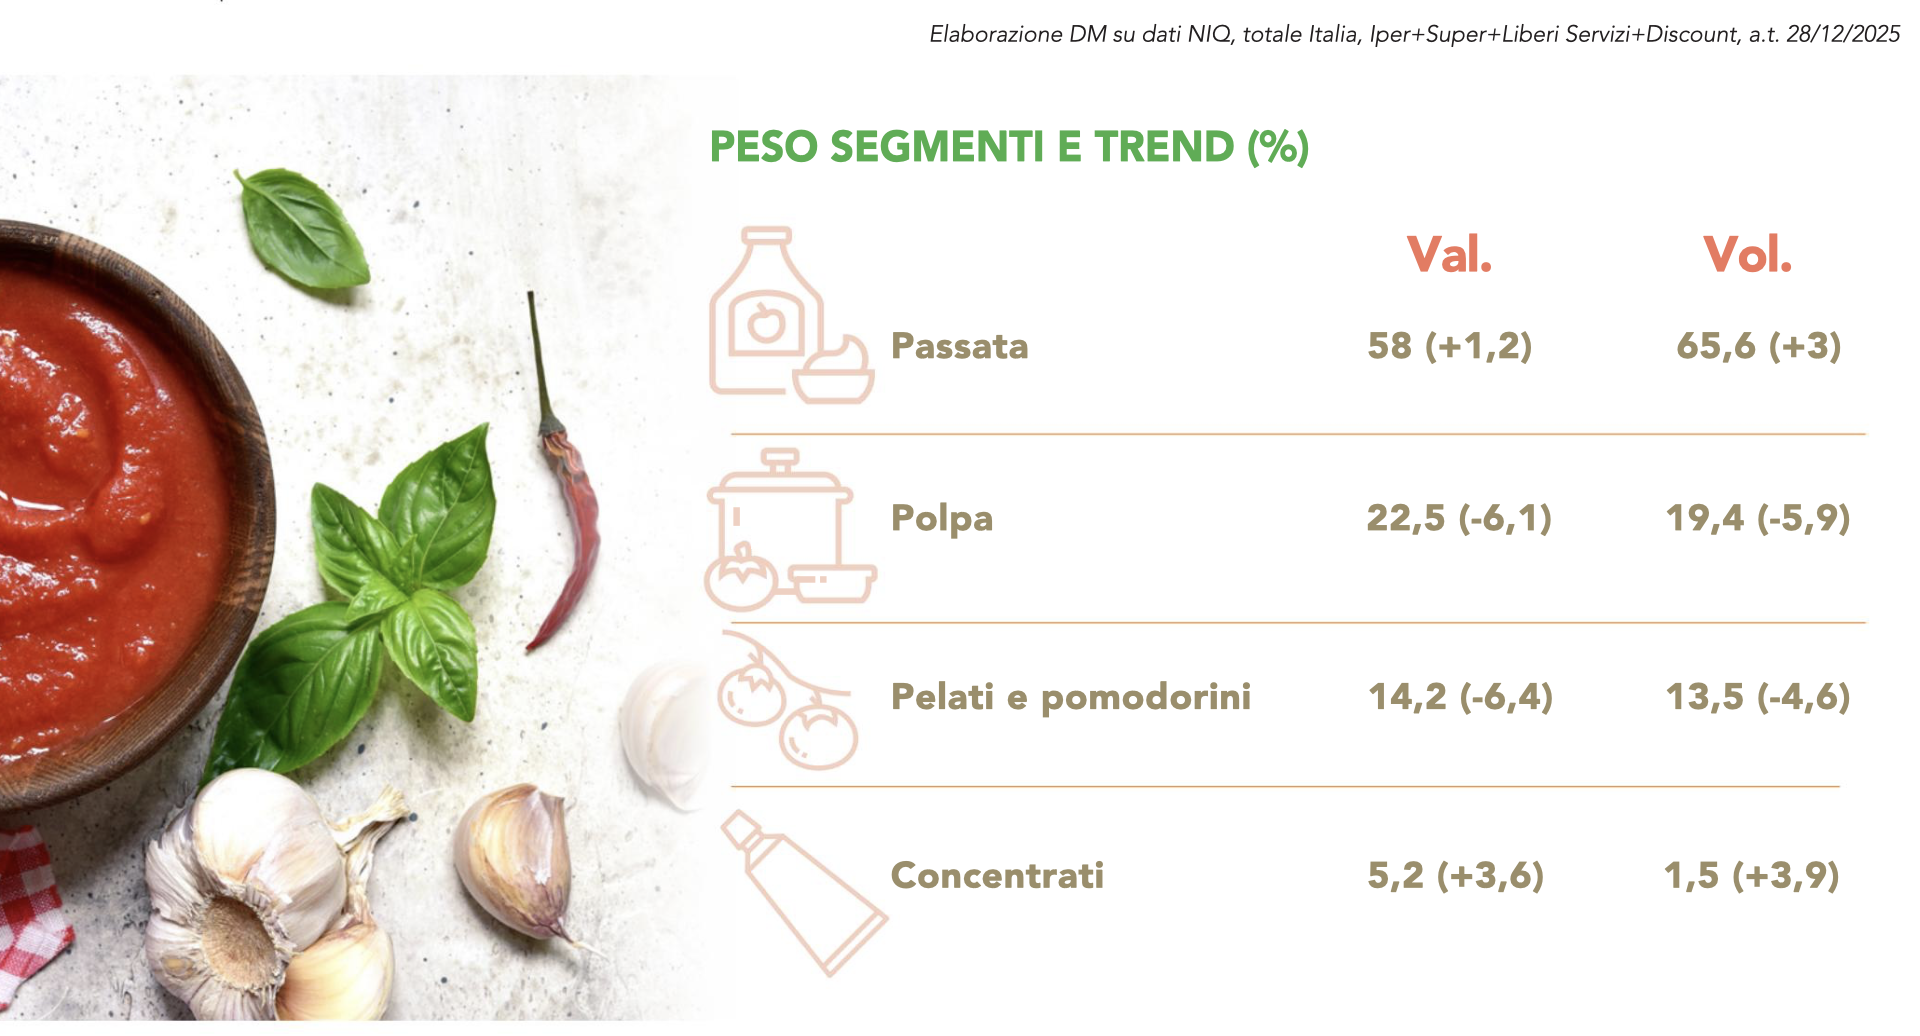 (+1,1% in value, +1,8% in volume and +1,6% in packs). However, it was brick-pack tomato passata (volume share 6,7%) that stood out for its performance in the last year ending, with an increase of 3,2% in value, 14,2% in volume and 4,5% in packs.” The tomato pulp segment, second in terms of contribution to volume, records trends opposite to those observed for passata; due to a promotional decline of 2,5% (promotional intensity by volume 35,5%), sales declined in value (-6,1%), volume (-5,9%) and packs (5,5%). The loss does not affect only canned tomato pulp, as the main sub-segment (volume share 16,2%), but also tomato pulp in glass and brick packs. Next is the peeled tomatoes and cherry tomatoes segment, which, like the previous one, saw sales decrease compared with last year (-6,4% in value, -4,6% in volume and -3,3% in packs). Here too, the main cause of the loss was promotions, whose intensity declined by 1,8%. Finally, tomato purées, despite their marginal share, recorded positive performance (+3,6% in value, +3,9% in volume and +4% in packs), thanks to the combined contribution of promotions (promotional intensity by volume 6,3%; +1,5%) and assortment (2,7 SKUs; +2,7%).
Read more about DM Magazine February 2025
This article was translated from the original Italian version with the assistance of artificial intelligence. In case of discrepancies, please refer to the original Italian version.
