Ovs: first half above 877 million euros (+10,7%). All brands in positive territory
Ovs: first half above 877 million euros (+10,7%). All brands in positive territory
- Information
Ovs Group continues to perform strongly and consistently, with very significant growth also in the second fiscal half, February-July 2026.
Adjusted EBITDA stands at +17,5%
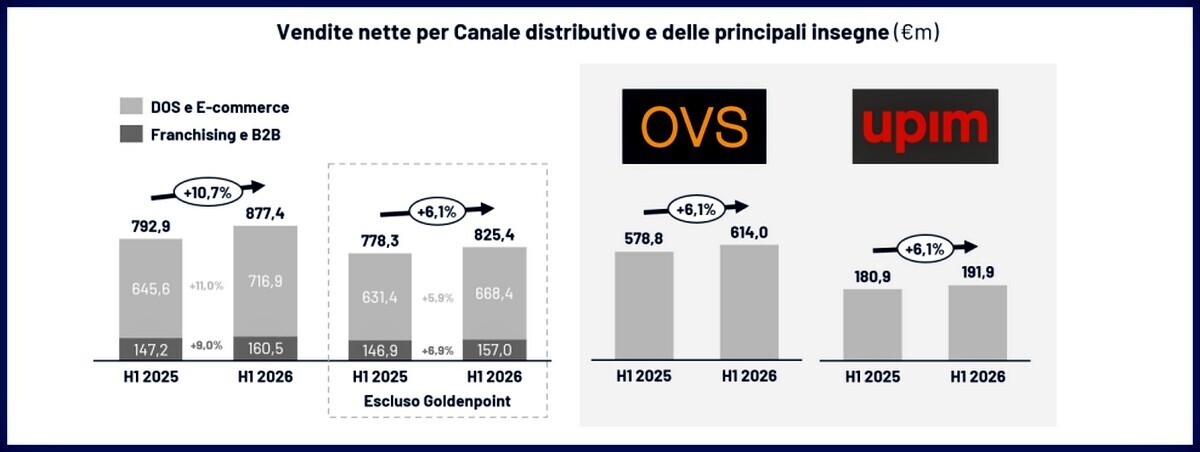
Within the organic perimeter, that is, on a like-for-like basis and excluding acquisitions, net sales reached 825,4 million (+6,1% compared with the corresponding period). This follows a second quarter (May–July) that maintained a significant growth rate (+4,9%).
Adjusted EBITDA rose to 114,1 million (+17,5%, an increase of 17 million), taking the EBITDA margin from 12,5% to 13,8% (+135 basis points).
How is the integration of Goldenpoint progressing?
The integration of Goldenpoint, acquired in 100% in July 2025, is progressing successfully.
Sales from the underwear and beachwear brand are showing a till performance up by more than 10% compared with the same period in 2025 and, here too, gross operating profit is positive.
This momentum, combined with an increasing commercial margin, boosted by purchasing synergies, brought Goldenpoint’s EBITDA alone into positive territory, compared with the loss of several million euros recorded in February–July 2025.
Ovs sales on the current store network recorded +11%
On a consolidated basis, and on the current store network, net sales across the Ovs group reached 877,4 million (+10,7% year-on-year) with adjusted EBITDA of 114,3 million (+12,3%).
The cash profile over the last two quarters shows an improvement of 15,3 million euros, while adjusted net financial debt fell to 240,1 million euros, a reduction of 53,6 million compared with 293,6 as at 31 July 2025, generating a further significant improvement in the leverage ratio.
Stefano Beraldo
Adjusted net profit amounted to 49,1 million euros, with a change of +7,7%.
“The second half of the financial year 2026 – a statement reads – got off to a satisfactory start. To date, sales for the autumn season are in line with those of the last two financial years, which were very robust. The reception of the new collections has been very good, particularly the performance of our brands, confirming expectations of a favourable second half”, when August, the second month of the summer sales, will also be accounted for, among other things.
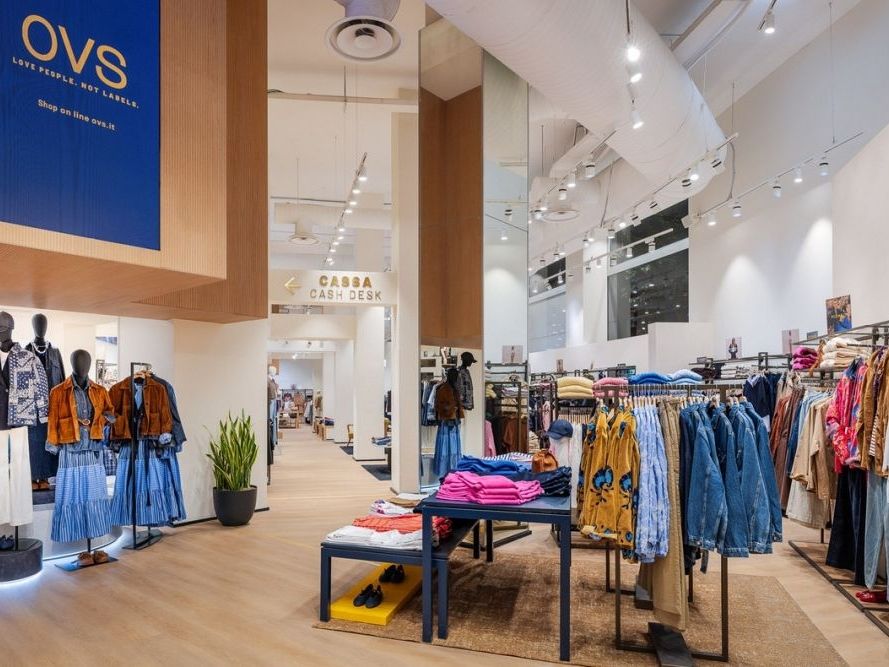
Moreover, as is known, the largest flagship store operating under the Ovs banner was recently opened in Dubai, in the first few days of September, and it is showing a strong initial performance, despite the challenging geopolitical situation at present.
As the CEO Stefano Beraldo points out: “During the February–July 2026 period, all brands grew, particularly thanks to the increase in like-for-like sales; the group continues, in fact, to outperform the clothing market, which grew by 1,5% during the period”.
“The Ovs world – Beraldo continues – has continued to work on developing and enhancing its brand portfolio, each with a distinct identity and aimed at different customer targets”.
Shaka is racing, while Upim is driving Gallery
There would be many facts to report, but let us limit ourselves to the drive that the fast-fashion queen is giving to the development of the Shaka mono-brand network (now 13 stores and 20 by year-end) and to the evolution of Upim, within which the new Upim Gallery format is gaining ground. It has added the Oriocenter store to its network.
The Upim banner, with a like-for-like change of +6,1, matches the performance of the flagship brand, while the channel, over the six-month period, rose to 191,9 million in net sales, compared with 180,9 in the corresponding period.
“As a result of all this – the company explains – expectations for the second half of the financial year are favourable and margins may benefit from the good reception of the autumn collections. The forecast of cash generation for the full 2026 is therefore confirmed, with a further improvement compared with 90 million euros in 2025”.
This article was translated from the original Italian version with the assistance of artificial intelligence. In case of discrepancies, please refer to the original Italian version.