


The stationery sector focuses on innovation and personal expression
The stationery sector focuses on innovation and personal expression
- Information
Against a backdrop made more complex by declining birth rates and digitalisation, companies in the stationery market are offering innovative, high-quality solutions capable of interpreting and responding to the needs of consumers of all generations, with particular attention to younger people.
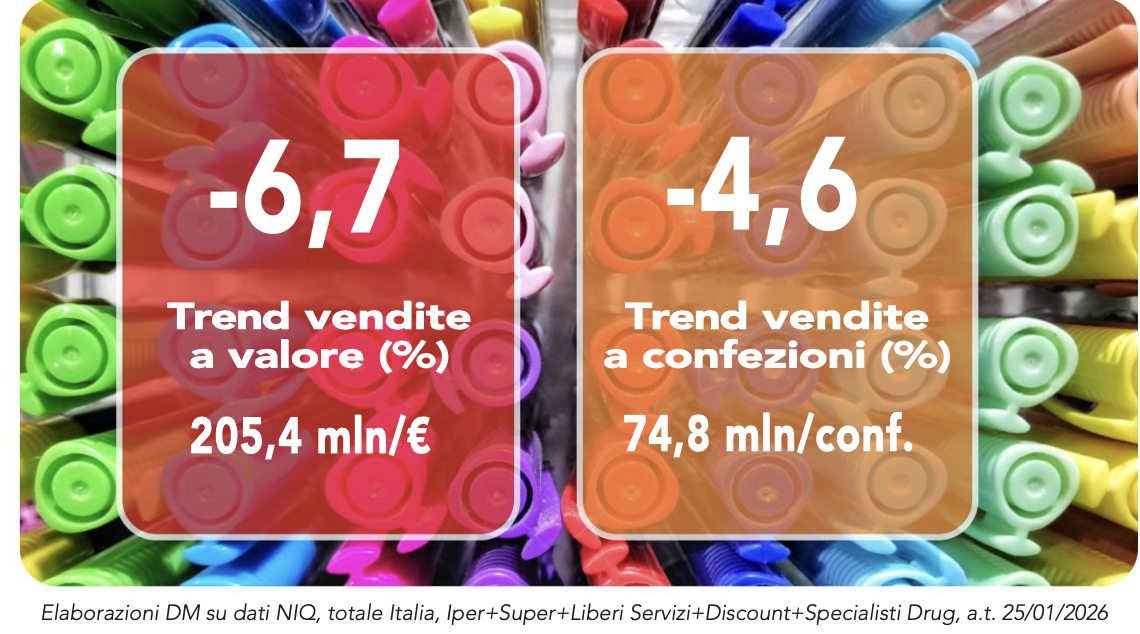 In the year ending 25 January 2026 (NIQ data, total Italy, Hypermarkets+Supermarkets+Free Service+Discount+Drugstores), the sector ended the period in clear contraction: turnover fell to almost 205,4 million euros (-6,7%) and volumes declined to 74,8 million packs (-4,6%). The context remains deflationary, with an average price of 2,74 euros per pack (-2,2%), while promotional pressure remained broadly stable (+0,3%) at a share of 17,4 points and the average assortment fell to 25,6 items per outlet (-1,1%).
Geographical areas and distribution channels
«From a geographical perspective – says Benedetta Ballabio of NIQ – Area 0,9%, the leading area in terms of sales location by packs (15,3), recorded a decline in value (1,9%) and packs (+2,2%), with the average price falling (44,2%), while promotional intensity increased by -8,4% and reached -3,8% percentage points. Area -4,8%, second in terms of sales location by packs, with a share of 1,4%, declined both in value (20,9) and packs (-5,4%), partly owing to a slight reduction in promotional activity (20,4%; -0,7%) amid falling average prices (-1,7%). Area 2, which accounts for 23,9% of packs sold, followed a trend in line with the national average: value sales at -7,8%, packs at -5,5%, an average price of -2,5% and promotional intensity increasing (14,6%; +1,2%). Area 4 moved in the opposite direction, accounting for 15,2% of packs and showing broadly stable value sales (-0,2%) and  growth in packs sold (+1,7%). Here, promotional pressure fell, reaching the stated level, and the average price decreased, while the assortment expanded slightly.» Looking at the channels, hypermarkets, the leading channel in terms of sales location by packs, showed a decline: turnover fell, packs decreased and the average price declined. Promotional activity remained high and increased to the stated level; while the assortment, though broad, contracted. Supermarkets, second in terms of sales location by packs (22,4%), also recorded negative changes: -4,8% in value, -2,2% in packs and an average price of -2,6%, with promotional levers increasing (10,1%; +0,7%). Free-service outlets remain a residual channel, accounting for 1,7% of packs sold. Discount stores (11,6% sales location by packs), on the other hand, showed a strong price-volume trade-off: turnover fell by 3,5%, against a marked decline in packs (-12,2%), while the average price rose significantly (+9,8%); the assortment expanded and promotional activity remained stable. Finally, drug specialists, which account for 20,1% of packs, ended the period with -5,7% in value and -4,3% in packs, in a context of a slightly lower average price and declining promotional intensity (26,1%; -2,9%).
Segment performance
Within this framework, the leading segments in terms of turnover (writing, writing paper and school accessories) account for much of the overall performance. «Writing – explains Benedetta Ballabio – remains the leading segment, with a value of 71,3 million euros, down 5,3%, against a reduction of 6,4% in packs sold and an average price increase of 1,1% (2,73€). Promotional activity intensified (16%; +1%), while the average assortment decreased (13,3 items; -3%). Within this segment, the pens sub-segment, with turnover of approximately 25,6 million euros, held up well: turnover was slightly down (-0,9%) and volumes increased (+1,2%). The complementary categories were weaker, such as  that of pen refills (-20,8%), highlighters (-11,2%), markers (-9,2%), pencils (-8,4%) and correction products (-10,9%). The case of pencils is particularly notable, with the average price rising sharply (+18,3%) and packs collapsing (-22,6%), a trend that significantly erodes turnover.» Writing paper, on the other hand, reached 50,3 million euros (-8,1%), with packs at -3,7% and a marked deflationary effect on the average price (-4,7%, equivalent to 1,91€). Promotional activity remained virtually stable (20,2%; +0,3%) and the assortment expanded slightly (10,2 items; +1,2%). As for the sub-segments, notebooks (32,9 million euros) lost 6,3% in value, with volumes slightly down (-0,9%), mainly reflecting price pressure (-5,5%). Drawing albums also declined in value (-5,1%), but the most heavily penalised were notepads (-18,8%) and sticky notes (-16,3%). In school accessories (almost 44,1 million euros), the market fell by 6,3% while volumes remained unchanged (-0,1% packs): the average price fell by 6,2%, promotional activity decreased by 1,6% to 16,3 points and the assortment grew markedly (+8%). Within this segment, backpacks and school bags declined, with value sales down 16,5%, as did pencil cases, which fell by 4,6%, while school diaries represented the only positive contribution, with a strong increase of +7,8% in value and +12% in packs.
Read more about DM magazine March 2026
This article was translated from the original Italian version with the assistance of artificial intelligence. In case of discrepancies, please refer to the original Italian version.
