Sugar and sweeteners: segmenting the market adds value to the shelf
Sugar and sweeteners: segmenting the market adds value to the shelf
- Information
Product innovation and origin certifications are the levers for revitalising the Italian sugar and sweetener market, which finds its key to adding value in premium products.
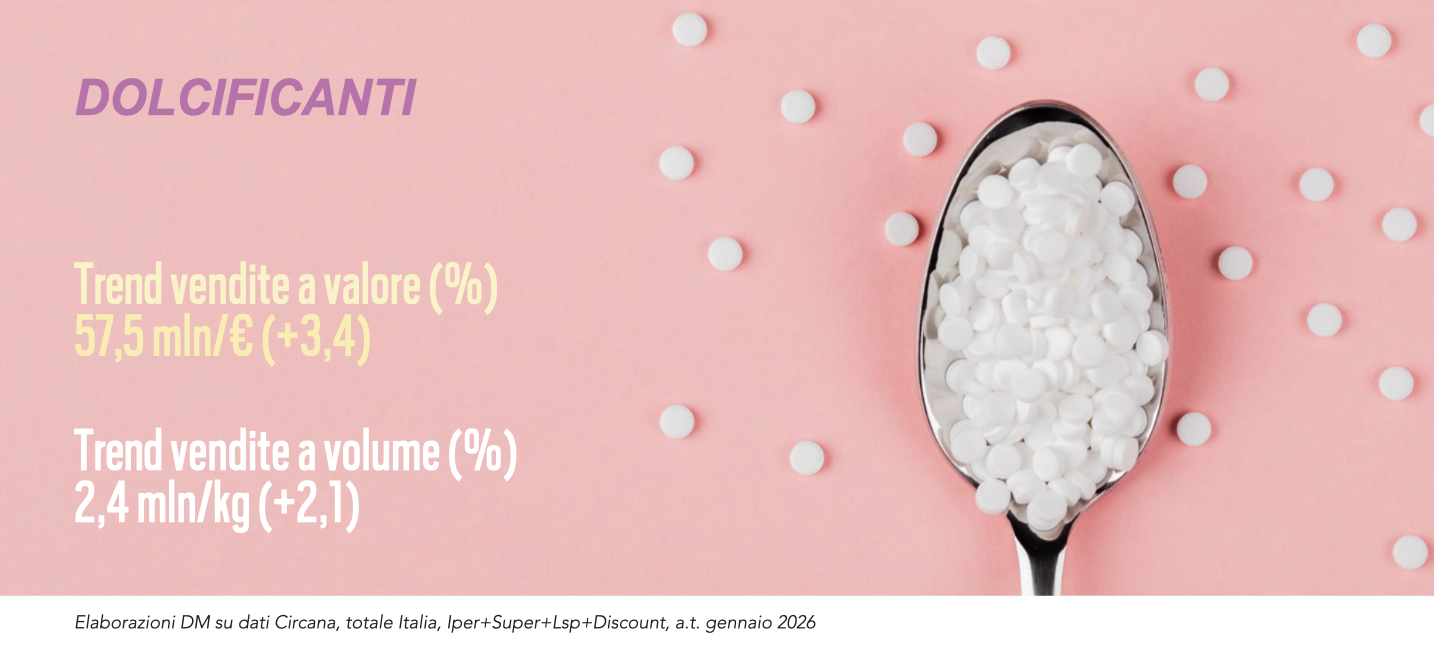
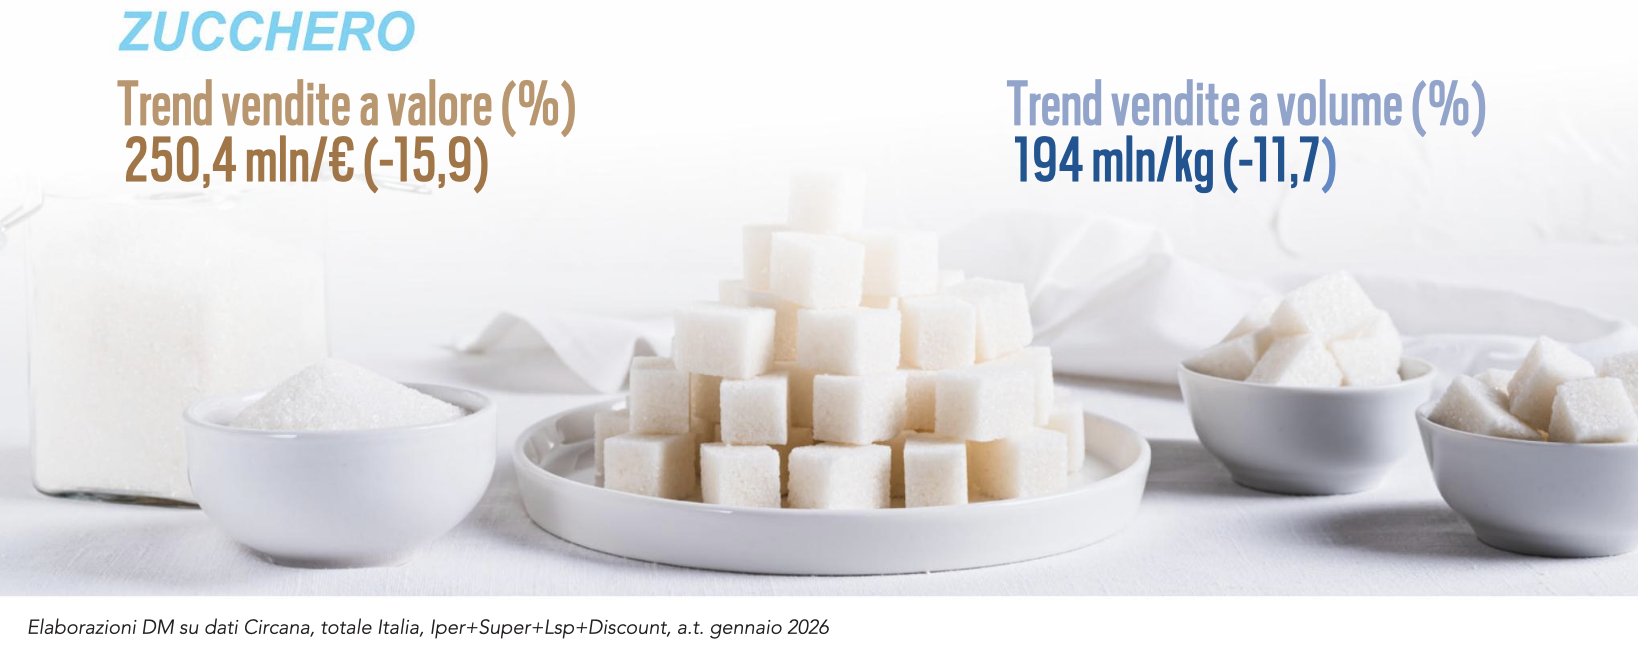 The sector, in the year ending in January 2026, showed different trends across the two macro-segments: while sweeteners recorded growth in both volume and value, sugar suffered a significant contraction. In the retail channel (Circana data, total Italy, Hypermarkets+Supermarkets+Lsp+Discount), sweetener sales by volume exceeded 2,4 million kilograms, an increase of 2,1% compared with the previous year, while total turnover stood at approximately 57,5 million euros, recording growth of 3,4%. This increase in value, slightly higher than that of volumes, suggests an inflationary effect or a greater orientation towards products with higher added value. Unlike sweeteners, the sugar market showed a marked decline. Sales by volume, in fact, fell by 11,7%, reaching approximately 140 million kilograms, while turnover, with a contraction of -15,9%, stood at almost 250,4 million euros.
Trends by geographical area and distribution channel
With regard to sweeteners, the geographical distribution of sales by value places the North-West at the top, with 30,2% of the value share and 36,2% by volume, followed by Centre and Sardinia with 11,3% of sales location by value and 10,5% by volume. The South accounts for 6,8% by value and 5,7% by volume, while the North-East holds 19,6% of the market value and 21,1% of its volume. As regards distribution channels, supermarkets remain dominant, accounting for 65,8% of the market share by value and 62,8% by volume; they are followed at some distance by discount stores (13,6% of sales location by value and 19,5% by volume), hypermarkets (11,2% by value and 11% by volume) and self-service stores (9,4% by value and 6,7% by volume). The geographical distribution of sugar, on the other hand, places the South as the most significant area, with 28,9% by value and 31,2% by volume; it is followed by the North-West, which accounts for 28,1% by value and 26,7% by volume, Centre and Sardinia, representing 23,3% of the value and 22,5% of the volume, and the North-East, with a share of 19,7% by value and 19,6% by volume. At distribution-channel level, supermarkets also account for most sales in the sugar segment, both by value (51,7%) and by volume (47,6%). Discount stores are the second most important channel, with the corresponding value and volume shares, followed by self-service stores and hypermarkets.
Segment trends
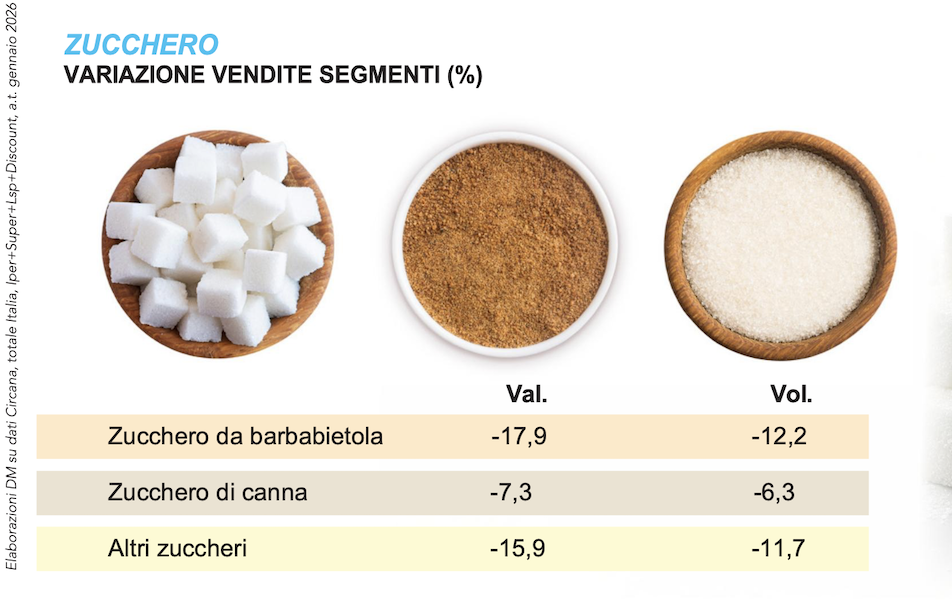 Within the sweetener market, there are sometimes significant differences between segments. Artificial sweeteners, the most important type in absolute terms, with over 840.000 kilograms and 33,6 million euros in turnover, show solid growth, with an increase of 5,4% in volume and 4% in value. The other natural sweeteners segment, although second in terms of volume at approximately 769.000 kilograms, generates significantly lower turnover, amounting to approximately 7,38 million euros, showing limited growth in volume (+1%) but a significant increase in value (+13%). Natural syrup sweeteners, on the other hand, are the only segment in decline, with a decrease of 3,1% in volume and 5,6% in value. Finally, stevia shows growth in volume (+1,6%), but a
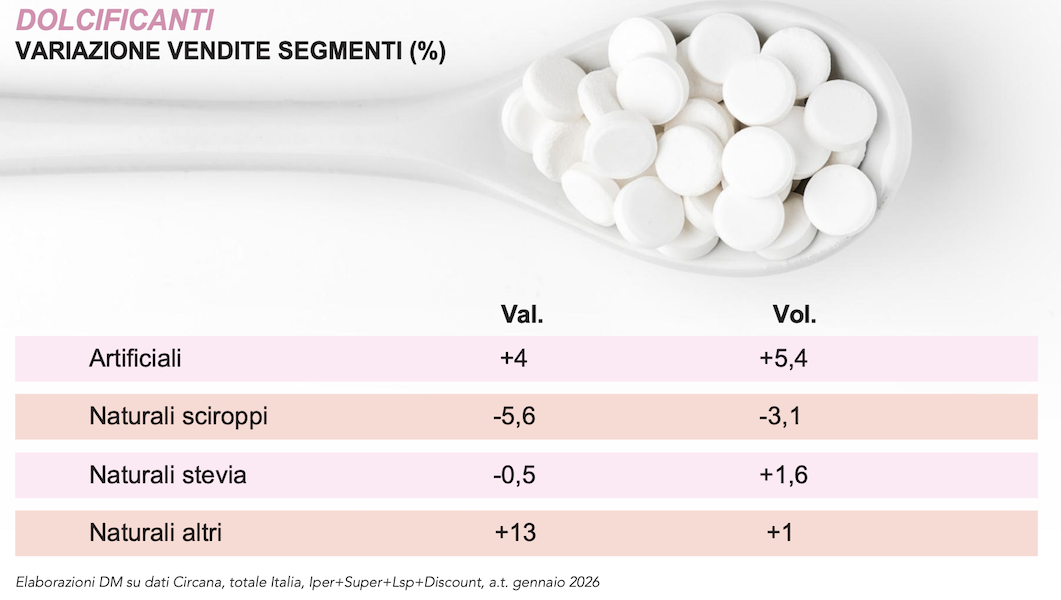 slight decline in value (-0,5%). In this context, the top three brands (Sperlari, Eridania and Valsoia) account for 49,6% by value, while private label holds 27,9%. As regards sugar, beet sugar, the leading segment by volume with over 176 million kilograms and by value with 198,8 million in turnover, undergoes the most significant contraction (-12,2% by volume and -17,9% by value), followed by cane sugar (-6,3% by volume and -7,3% by value). The other sugars segment, with a negligible share in absolute terms, is instead the only one to grow, both in volume and value, with an increase of 6,7% in both cases. Here, the top three players (Eridania, Italia Zuccheri, Sadam Zuccherifici) account for 37,8% of the market by value, while Mdd holds 44,5% of the market share.
Read more about DM Magazine March 2026
This article was translated from the original version in Italian with the assistance of artificial intelligence. In case of discrepancies, please refer to the original version in Italian.