


Oil volumes are breathing again. EVO remains the sector’s driving force
Oil volumes are breathing again. EVO remains the sector’s driving force
- Information
To support the oil market, companies are banking on the recovery of extra virgin olive oil consumption, while promotional pressure and MDD seek to mitigate the impact of prices.
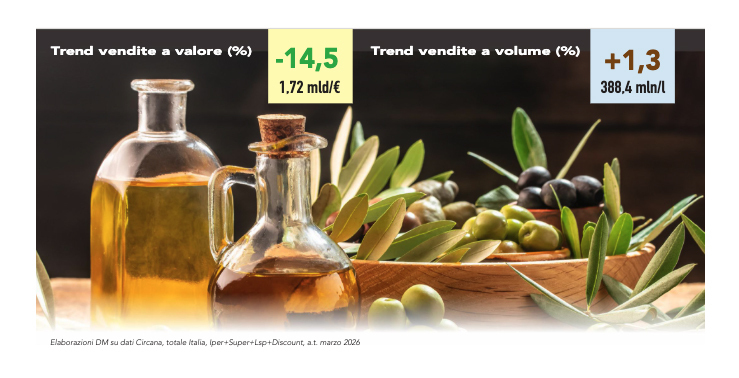 In the year ending in March 2026, the sector (Circana data, total Italy, Hypermarkets+Supermarkets+Free-service outlets+Discount stores) showed signs of recovery in terms of volumes, with year-on-year volume growth of 1,3%. Overall, more than 388,4 million litres of product (olive oil+seed oil) were sold. Total turnover, on the other hand, stood at 1,72 billion euros, nevertheless recording a sharp decline of 14,5%, linked to the gradual easing of the inflationary peaks that had characterised previous seasons.
Geographical areas and distribution channels
The geographical distribution of sales by volume sees the South in the lead, with 30,2% of volumes and 23,8% of value. It is followed by the North-West, which accounts for 26,3% of volumes and 29% of market value. Central Italy+Sardinia represent 24,3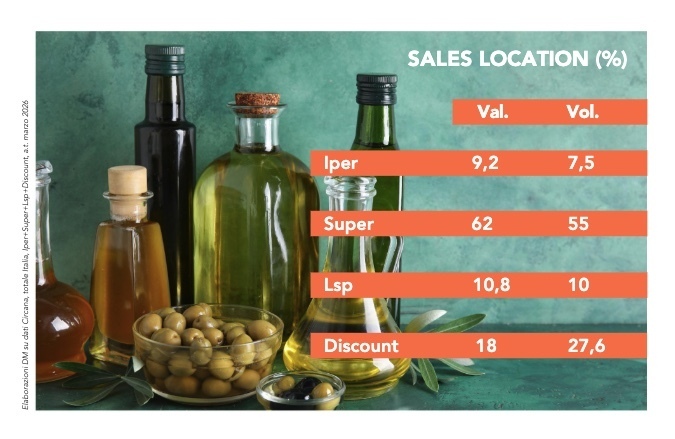 % of volume and 25,1% of value, while the North-East completes the picture with a share of 19,1% by volume and 22,1% by value. As for distribution channels, supermarkets confirm their absolute centrality, handling 55% of volumes and 62% of total value. Discount stores are the second most important channel, with a share of 27,6% by volume and 18% by value. They are followed by free-service outlets, with 10% by volume and 10,8% by value, and hypermarkets, which rank last with 7,5% of volumes and 9,2% of value.
Segment performance
Within the market, the various segments show divergent dynamics. Extra virgin olive oil (EVO) represents the driving force of the sect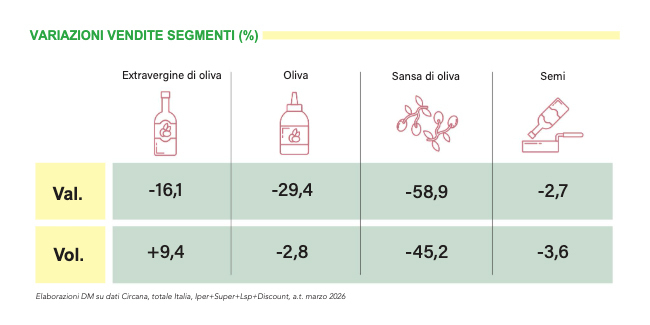 or, with more than 168,7 million litres sold (+9,4%) and 1,19 billion euros in turnover, down 16,1%. Seed oil is the second-largest segment by volume (201,9 million litres), but records a decline of 3,6% in quantity and 2,7% in value. Olive oil shows a contraction in volumes (-2,8%), but above all in value (-29,4%). Finally, pomace oil posts the most critical trend, with volumes plunging by 45,2% and value by 58,9%. The competitive landscape features a massive presence of private label, which holds 31% of the market’s value. Among branded producers, the top three players (Monini, Farchioni, Deoleo) collectively cover 19% of the market by value.
Read more about DM Magazine May 2026
This article was translated from the original Italian version with the assistance of artificial intelligence. In case of discrepancies, please refer to the original Italian version.
