


Meat: growth of quality and national-origin supply chains
Meat: growth of quality and national-origin supply chains
- Information
Consumption in the meat sector is growing both in value (+3%) and in volume (+1,7%). Classic cuts, such as sliced chicken, and production segments that certify animal welfare are preferred.
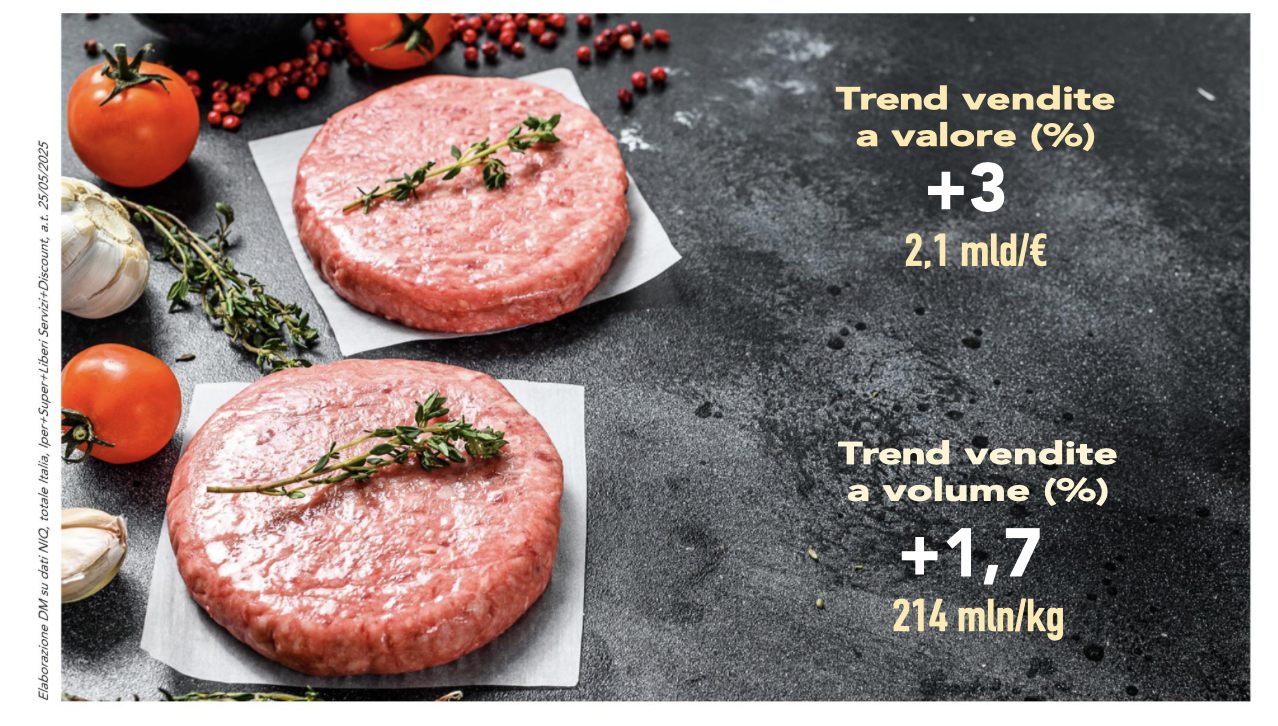 The meat market in Italy (Hypermarkets, Supermarkets, Free-Service Stores and Discount Stores) reached a turnover of almost 2,1 billion euros in the latest year ending 25 May 2025, recording an increase in turnover of 3%. Growth in value was accompanied by a positive trend in volume as well (+1,7%), for a total of 214 million kilograms sold. In this context, the expansion of the range (29,5 SKUs; +3,2%) played a crucial role in supporting growth.
Performance by geographical area
Growth in the category occurred across all geographical areas. Area 1 is leading,
says Elena Pezzotti of Nielsen IQ, which, with the largest sales location by volume (34,1%), saw increases not only in sales by value (+2,7%) but also in sales by volume (+1,1%). In second place, with a sales location by volume of 26,1%, Area 2 recorded growth in value of 1,9% and in volume of 0,7%. In third place is Area 3 (21,8% share), with a positive trend slightly above the market average (+3,3% in value and +2% in volume). Finally, Area 4, with a smaller sales location by volume of 18%, recorded an increase well above average: +5,4% in value and +4% in volume. In this context, once again, growth in the average number of products proved fundamental in supporting the performance of the geographical area (19,5 SKUs; +5,5%).
Discount stores lead in market share
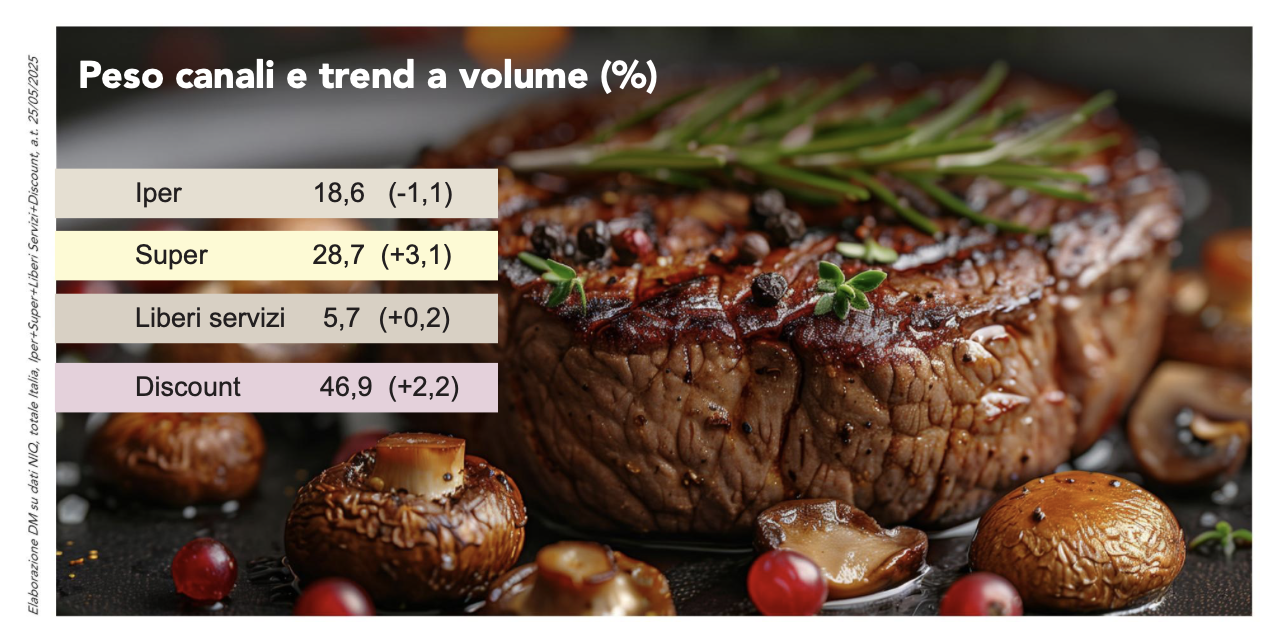
Among the channels, discount stores rank first for sales location by volume (46,9%), recording an increase in turnover of 3,3% as well as in volumes sold (+2,2%). The silver medal goes instead to supermarkets (28,7%), which stand out for highly positive performance regardless of the unit of measurement (+4,2% in value and +3,1% in volume). Hypermarkets contribute 18,6% of sales by volume, with a growth trend in value (+1,8%) but not in volume (-1,1%). In this case, despite the expansion of the range, the decline in promotions had a negative impact on the channel's performance (promo intensity by volume 29,1%; -2%). Finally, free-service stores, with a sales location by volume of 5,7%, recorded substantial stability in both sales by value (+0,2%) and by volume (-0,1%).
Performance of the segments
The growth recorded for the category as a whole occurred across almost all of its constituent segments. The meat market by contribution to volume
— continues Elena Pezzotti — consists of the following segments: poultry and rabbit (66,9%), beef (17,5%), pork (15%), horse meat (0,5%) and sheep and goat meat (0,2%). The poultry and rabbit segment, representing 2/3 of the market, has a predominant influence on the sector's dynamics and records positive trends both in value and volume, equal to +0,7%. As regards the main offering, fourth-stage poultry processing (volume share 29,5%) recorded negative trends (-0,9% in value and -1% in volume), unlike chicken (volume share 20%), which showed positive performance above average (+3,6% in value and +4,1% in volume). Once again, the range proves to be a fundamental lever for growth, also supported by promotional activity.
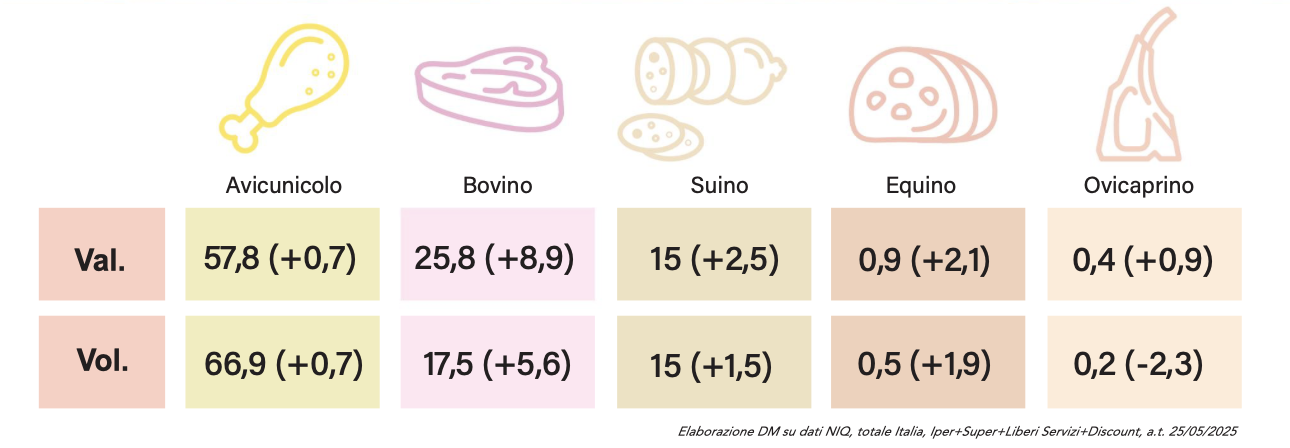 The beef segment, second in terms of contribution to volume, shows positive trends, higher than those of poultry and rabbit, both in value (+8,9%) and in volume (+5,6%), driven almost exclusively by third-stage beef processing (volume share 17,1%; +8,7% in value and +5,3% in volume). Pork, with a volume share similar to that of beef (15%), saw sales increase by 2,5% in value and 1,5% in volume.
Read more about DM Magazine September 2025
This article was translated from the original Italian version with the assistance of artificial intelligence. In case of discrepancies, please refer to the original Italian version.
