


Sweets and chewing gum: impulse drives the sector
Sweets and chewing gum: impulse drives the sector
- Information
In the sweets and chewing gum market, consumers favour impulse purchases and seek innovative products capable of satisfying the palate. Attention nevertheless remains firmly focused on price, with consumption being rationalised.
In the year ending 24 August 2025, the sector generated turnover of more than 824 million euros, recording a value trend of +1,9% compared with the previous year, following an increase in the 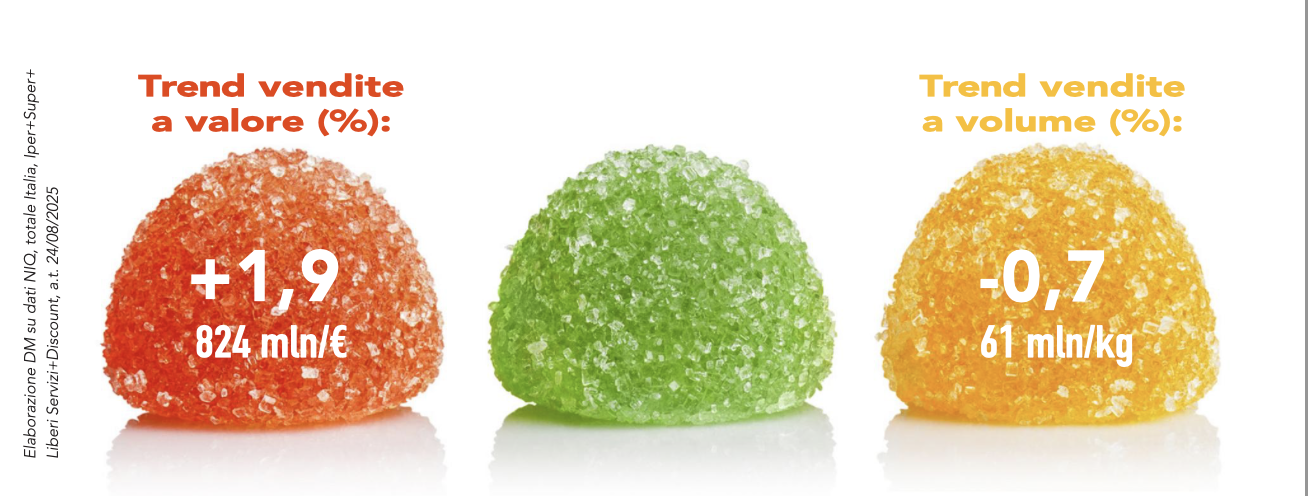 average price, amounting to +2,7%. Sales volumes, on the other hand, experienced a slight decline (-0,7%), for a total of 61 million kilograms marketed, despite a positive trend in packs (+1,1%). The assortment per outlet (+2,2%) and promotional intensity, amounting to +0,6 points, both increased. (NIQ data, total Italy, Hypermarkets+Supermarkets+Free Service+Discount).
Geographical areas and distribution channels
Value growth is widespread, both across channels and geographical areas. «The largest increase was recorded by Area -2,8% (-3,8%) – says Andrea Rana of NIQ – which also recorded a positive trend in volumes (+2,4%), unlike the other areas, where quantities sold declined compared with the previous year. Area 1 remains the most important market, accounting for 32% of turnover and 31,6% of volumes, despite showing a greater decline (-2%) in quantities sold than the other markets. It is followed in importance by Area 2 (23,4% of turnover and 24,1% of volumes), which has 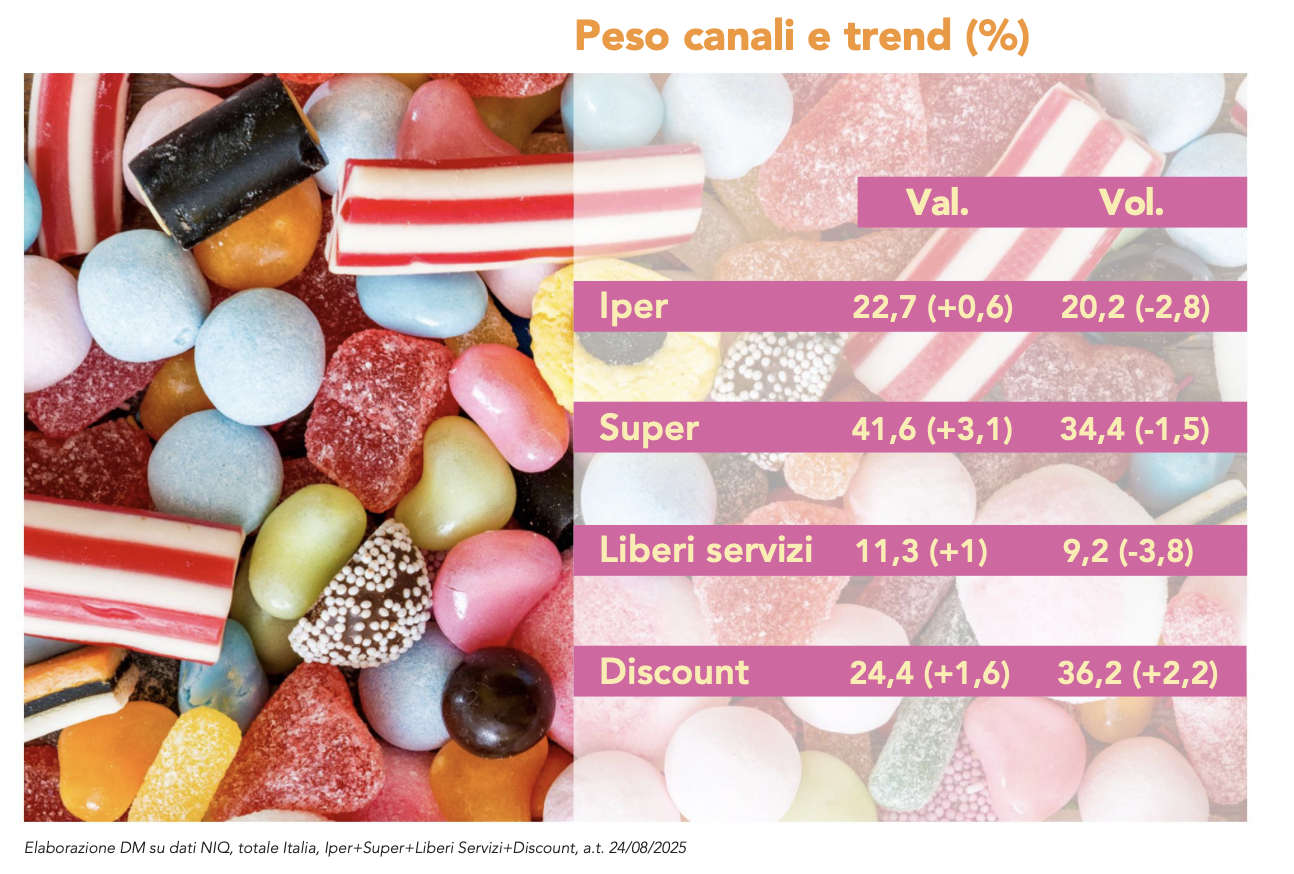 average ranging per outlet (92,5), equal to that of Area 1 and higher than in the other areas. Area 3 ranks second for value growth (+2,1%), following a greater increase in the average price (+3,5%)». Within the distribution channels, supermarkets, which account for 41,6% of category turnover, recorded the highest growth in turnover (+3,1%), driven by an increase in the average price, amounting to +4,7%. In terms of volume, discount is the only growing channel (+2,2%), confirming its position as the main market for quantities sold (36,2%); within this channel, the average price declined (-0,6%), while promotional incidence (+2,7 points) and the average assortment per outlet (+3,4%) increased. Hypermarkets and free-service outlets, finally, are losing importance within the sector, with negative trends in sales volumes, respectively at the levels indicated above, while free-service outlets recorded the strongest inflationary effect (+5,3%).
Segment performance
Sweets are the main market, generating 71,9% of turnover and 90,5% of quantities sold. They recorded a positive trend in turnover (+1,9%) following a price increase (+2,9%), which stood at 10,68€/kg. Sales volumes, on the other hand, declined (-1%). «Hard and filled sweets and gummy sweets are the main segments – Andrea Rana continues – accounting for 79,6% of sweets turnover and 70,5% of volumes. The former recorded the 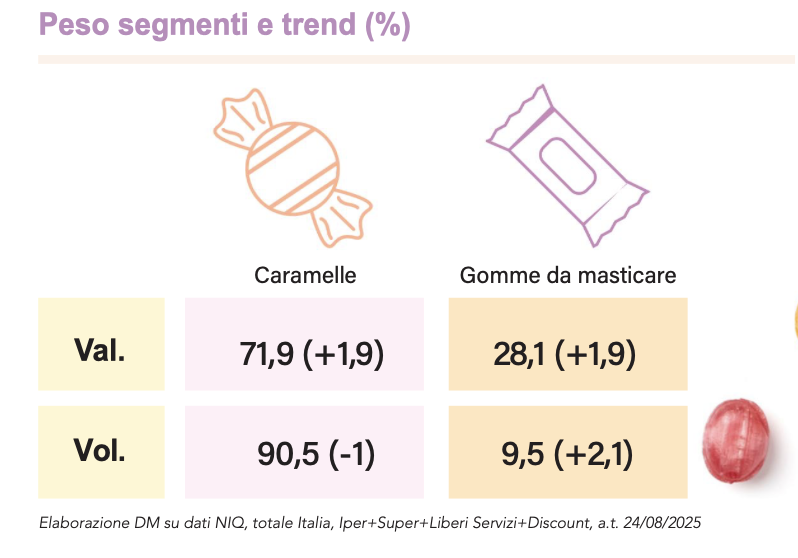 highest value growth within the category (+3,7%), partly due to an inflationary effect of +3,9%, while the latter grew less in terms of turnover (+2,2%) but showed an increase in the average assortment per outlet (+6,1%). The greatest volume growth occurred in the jelly sweets segment (+2,8%), which is the third most important, accounting for 7,5% of turnover and 11,2% of sales volumes. These first three segments showed growth in the pack trend (respectively +2,4%, +1,3% and +1,9%), while the remaining types of sweets (other sweets, lollipops, toffee and fudge, cotton) recorded a decline also affecting volumes and turnover, with a reduction in the average price (except for lollipops, where it increased by 6%)». Milk tablet sweets, on the other hand, grew, increasing by 2,1% in sales volumes despite their still marginal importance within the category. Chewing gum, on the other hand, generated 28,1% of turnover and 9,5% of volumes, showing positive trends both in value (+1,9%) and volume (+2,1%), with prices remaining stable compared with the previous period (39,69€/kg). Driving this increase was the sugar-free segment, which represents approximately 90% of the category. Regular chewing gum, on the other hand, showed a slight decline in volumes (-0,3%), but an increase in average ranging per outlet (+12,8%).
Read more about DM Magazine October 2025
This article was translated from the original Italian version with the assistance of artificial intelligence. In case of discrepancies, please refer to the original Italian version.
