IV and V range: plenty of health without effort. Ready-to-eat products are growing
IV and V range: plenty of health without effort. Ready-to-eat products are growing
- Information
Consumers, increasingly aware of the nutritional benefits of fourth- and fifth-range products, do not want to invest time in processing vegetables, which is often lengthy and laborious. The choice therefore falls on ready-to-eat products, while the offering becomes more differentiated.
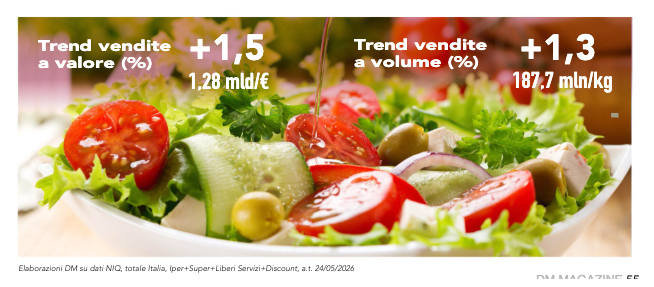 In the year ending 24 May 2026, the market generated total sales of approximately 1,3 billion euros, recording a positive value trend of 1,5% compared with the previous year. This growth was accompanied by equally positive performances in volume (+1,3%), with almost 188 million kilograms sold, and in units (+0,9%). In this context, the average price proved to be virtually stable (6,79 euros, +0,2%), with an increase in the assortment, amounting to 30,8 units and +0,9% (NIQ data, Total Italy, Hypermarkets+Supermarkets+Self-service stores+Discount stores).
Geographical areas and distribution channels
«The -1% area remains the most important territory for the category in terms of value and volume – explains Elisabetta Fabbo of NIQ –, in fact accounting for 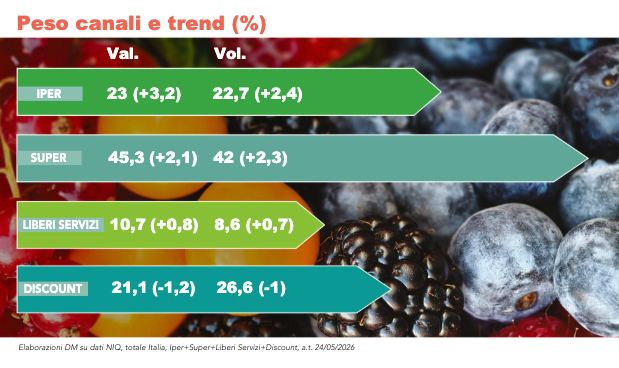 34,2% of turnover and 33,7% of kilograms sold, and recording positive performances, although below the market average (+0,7% in value and +0,9% in volume). It is followed by the 3 area, with a sales location in volume of 27%, characterised by substantial growth trends, both in value (+2,9%) and in volume (+2,8%). The 2 area takes third place in terms of contribution to volume (sales location 21,7%) and stands out for negative trends (-0,4% in value and -0,7% in volume). In this case, the lever that has proved supportive for the category has hit the North-East hard, where the average number of references on sale has fallen by 1,2%. Finally, the 4 area, with a sales location in volume of 17,6%, records growth in value of 3,8% and in volume of 2,2%». At channel level, supermarkets represent the main market in value terms, accounting for 45,3% of turnover and, together with hypermarkets (accounting for 23%), record the strongest trends. Within modern distribution, self-service stores instead show more limited growth both in value (+0,8%) and in volume (+0,7%). Discount stores are ultimately the real exception and, with a sales location in volume of 26,6%, record negative performances.
Segment performance
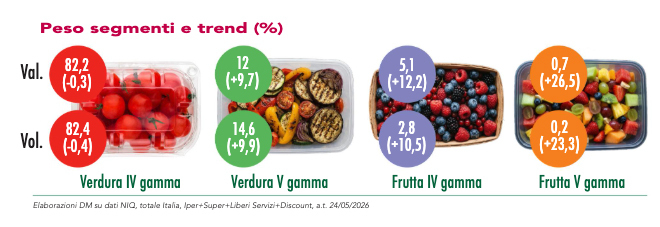 «For Italy as a whole – continues Elisabetta Fabbo –, 82,2% of turnover is made up of fourth-range vegetables, which nevertheless record a negative value trend (-0,3%) and volume trend (-0,4%). In this context, in addition to the decline in promotional activity, there has been a reduction in the average number of references on sale. Mixed/tender/crunchy salads, which represent the main offerings, are certainly driving the category's decline, while enriched salads are an exception, with a value share of 4,4%. Indeed, the segment records positive performances in value (+1,4%) and volume (+1,7%). The same situation can be seen for crudités, with more than substantial growth trends (+3,4% in value and +8,3% in volume)». The fifth-range vegetable segment proves to be the second most significant in value (12%) and volume (14,6%), growing (+9,7% in value and +9,9% in volume) thanks to assortment support (7,3 references and +3,8%). Fourth- and fifth-range fruit also records an increase, not only due to an increase in the references generally present at the point of sale, but also to promotions. These are in fact the only segments showing a positive change in promotional intensity.
Read more about DM Magazine September 2026.
This article was translated from the original Italian version with the assistance of artificial intelligence. In case of discrepancies, please refer to the original Italian version.