


Healthy breakfast products without sacrificing taste
Healthy breakfast products without sacrificing taste
- Information
Companies are responding to fatigue in the breakfast products sector with proposals that ride the main trends in mass-market consumption, from high-fibre and high-protein products to sugar-free options, promising equal enjoyment of the taste.
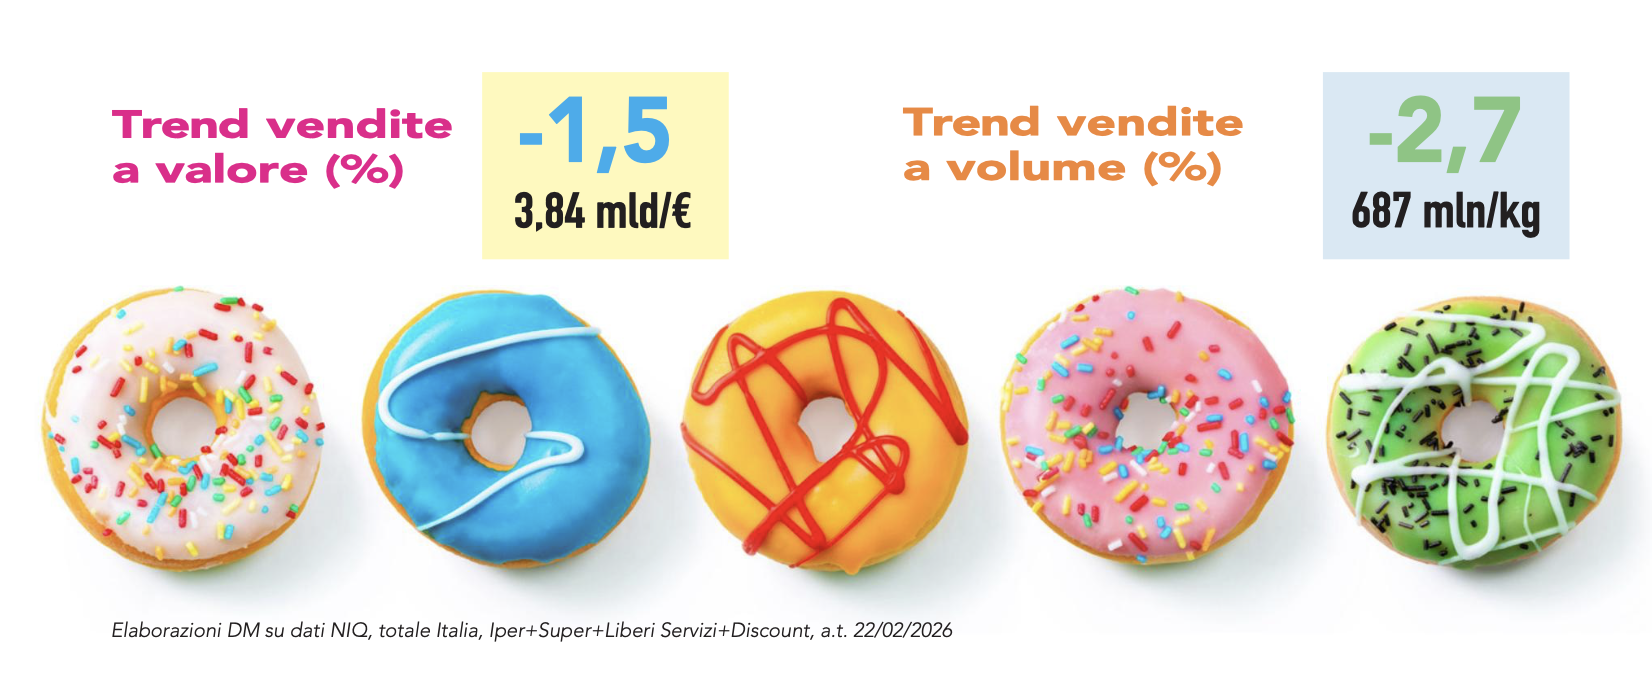 On Italian large-scale retail shelves, the sector is experiencing a year of adjustment: not a collapse, but a measurable slowdown. In the year ending 22 February 2026, total Italy turnover (NIQ data, Hypermarkets+Supermarkets+Free-service stores+Discount stores) fell by 1,5% to 3,84 billion euros, while volumes declined by 2,7% to 687 million: “A trend – says Ludovica Zarba of NIQ – that reflects more cautious consumption, partially offset by an average price per kilo rising by 1,2% (5,59 €/kg) and a slight increase in the average price per pack (+1%). The upward price trajectory was not driven by an excess of promotional tactics, which remain essentially stable/slightly down, with volume-based promotional intensity at 30,6% (-0,2%).”
Geographical areas and distribution channels
Geographically, the country is moving at different speeds. Area 4 is the most resilient: -0,4% in value and -1,8% in volume, a slowdown 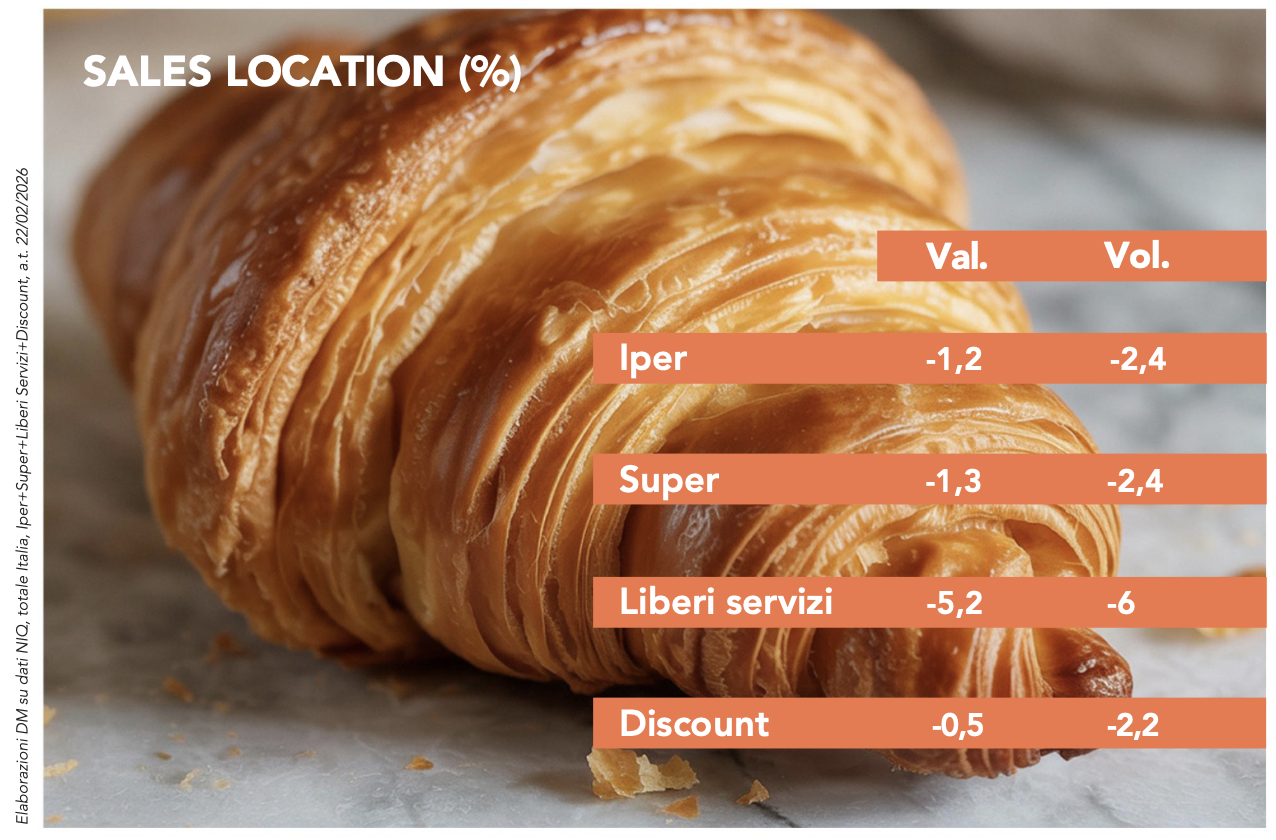 limited compared with the rest of the country. Area 1 and Area 2 are experiencing the sharpest correction (-2,2% and -2,1% respectively in value; -3,2% and -3,3% in volume), while Area 3 lies in the middle (-1,5% in value and -2,8% in volume). In summary, the resilience of the South and the islands is mitigating more cautious purchasing in the North and Centre. In terms of channels, hypermarkets are limiting the decline to 1,2% in value (-2,4% in volume), followed by supermarkets at -1,3% (-2,4% in volume). Free-service stores are faring worse, falling by 5,2% in value and 6% in volume, the result of shoppers rationalising their baskets in local shops. Discount stores, on the other hand, are holding their position: -0,5% in value, despite volumes contracting by 2,2%; a balance that confirms their role as a “shock absorber” when purchasing power is under pressure. “The picture that emerges – comments Ludovica Zarba – is of a market undergoing a slight but orderly correction: prices are rising moderately, promotions are not excessive, and consumption geography shows the South outperforming the North. As for channels, the hypermarket+supermarket pairing continues to be the category’s cornerstone, while traditional local shopping is going through a more difficult phase and discount stores remain the tactical refuge for families seeking structural value.”
Segment performance
The breakfast market clearly shows who is at the helm and who, instead, is falling back: biscuits are almost stable in value, snack cakes are retreating, breakfast cereals are growing and rusks are slowing sharply. “Breakfast cereals are changing course and returning to growth – continues the NIQ analyst –: turnover is up by 2,3% to 482,2 million euros, also supported by rising volumes (+1,5%) and a slight increase in the average price/kg (+0,8%). This is mainly thanks to muesli (+4,3% in value) and plain products (+3,6% in value), while enriched products remain slightly down (-0,5% in value). In short, we can glimpse a more functional, less sugary breakfast, with promotional intensity at +0,3%, signalling 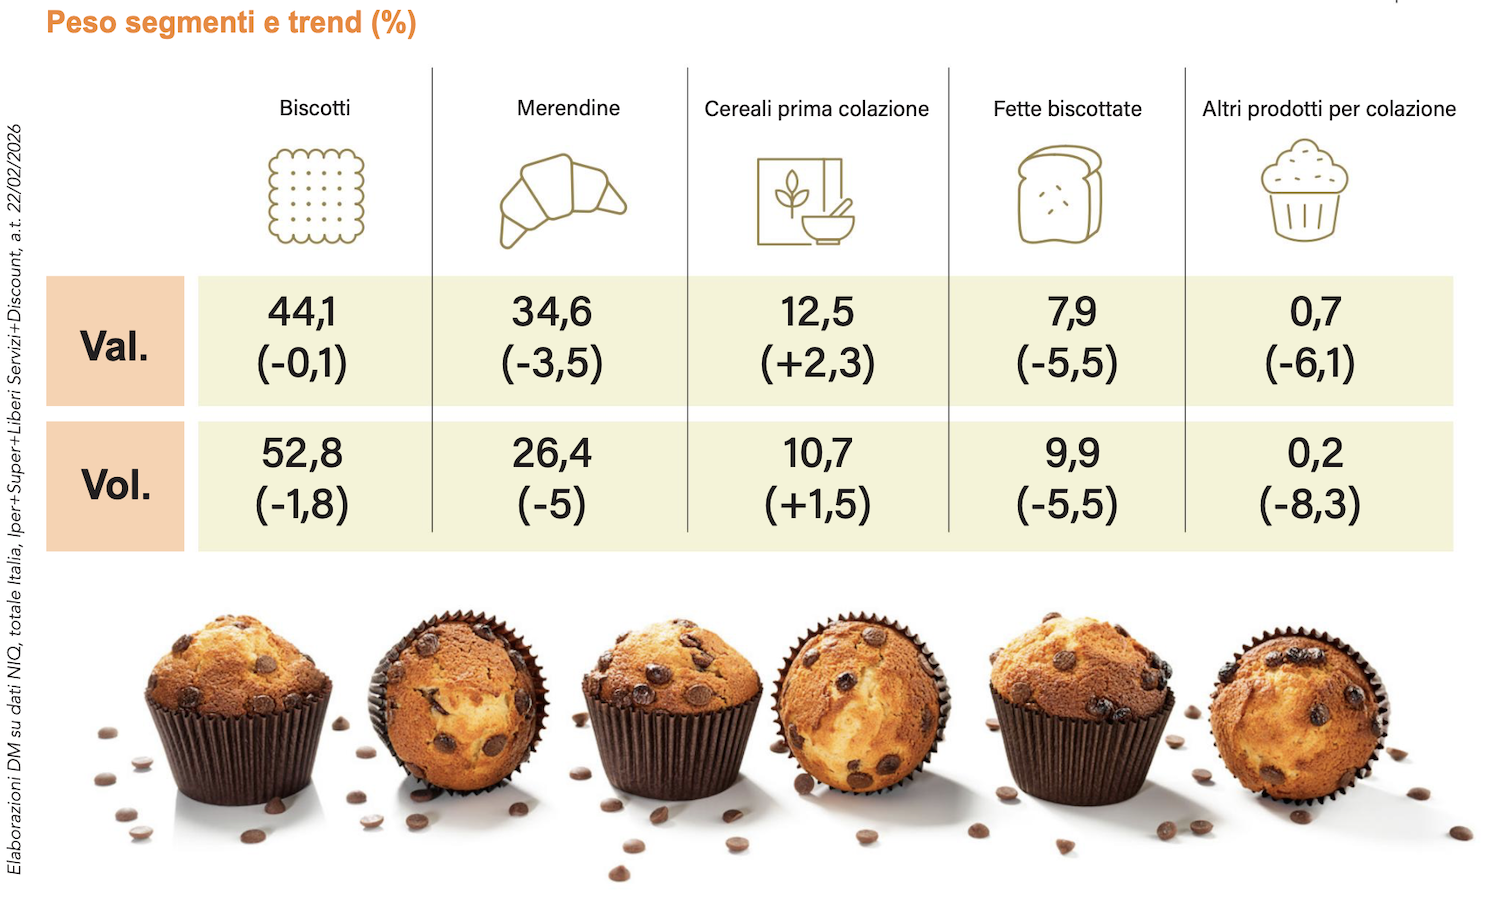 genuine demand rather than tactical pressure.” Biscuits, a pillar of the breakfast market, are holding up: value is close to parity (-0,1% at 1,697 billion euros), despite falling volumes (-1,8%). Supporting this resilience is a rising mix/price (+1,8% €/kg) and an assortment that continues to expand (the number of SKUs is up by 1,2%), while promotional activity is declining slightly. Within the category, traditional biscuits stand out, advancing by 0,1% in value despite falling unit sales, driven by enriched shortbread biscuits (+0,6% in value), while plain shortbread biscuits decline slightly (-0,5% in value), as does the wholemeal/multigrain segment (-0,4% in value). Health biscuits remain slightly down (-0,9%), consistent with a shopper who favours tradition when the budget becomes tighter. Snack cakes, on the other hand, are experiencing a more difficult year: turnover is down by 3,5% to 1,331 billion and volumes are down by 5%, with the average price rising moderately (+1,5%). The picture is not uniform, however: established blocks such as croissants (-6,7%), plumcakes (-4,5%), jam tarts (-7,8%) and, above all, puff pastries (-13,5%) are suffering. Two high-signal niches are bucking the trend: pancakes are achieving double-digit growth, amounting to +15% in value and +14,8% in volume, while other brioches are advancing by 9,7% in value. This is the story of a breakfast that allows itself “new” and more indulgent formats at the weekend, while trimming back on repetitive everyday purchases. Promotional leverage in the snack-cake segment remains substantially stable; therefore, the trend is genuinely consumption-driven. The rusk segment is the most troubled area. Turnover slips by 5,5% to 304,9 million euros and volumes fall by 5,5%, with an essentially flat average price/kg and easing promotional pressure (-8%). The contraction affects all subsegments: wholemeal (-5,6%), standard (-6,3%) and enriched (-5,2%), while lagaccio rusks limit the damage (-0,5%). “Seen in the background – concludes Ludovica Zarba – is a lower propensity to stock up on pantry products when the budget is under pressure. Finally, the other breakfast products category, small but indicative, loses 6,1% in value and 8,3% in volume, despite an increase in the average price: a sign that demand is postponing ancillary purchases in favour of the pillars of breakfast.”
Read more about DM Magazine April 2026
This article was translated from the original Italian version with the assistance of artificial intelligence. In case of discrepancies, please refer to the original Italian version.
