Flours and baking ingredients: quality and service win over price
Flours and baking ingredients: quality and service win over price
- Information
From speciality flours to gluten-free products and packaging solutions, the supply chain is responding to consumers’ greater knowledge by focusing on high-value-added products designed to make preparation and storage at home easier.
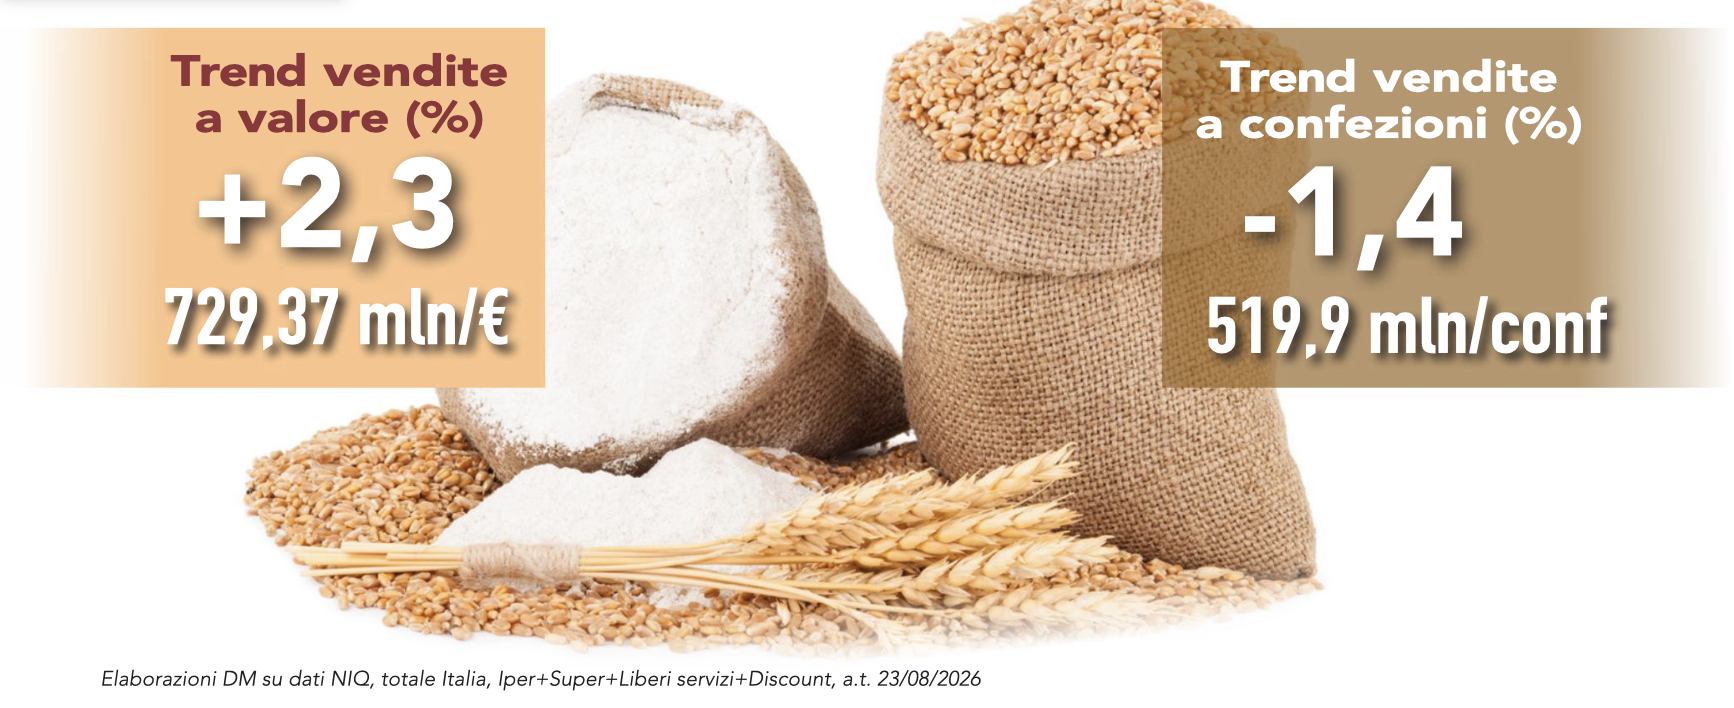 The market for flours and basic baking ingredients, in the year ending 23 August 2026, recorded value growth in modern distribution (+2,3%) but not in packs (-1,4%), due to the rising average price per pack (1,4 euros; +3,8%). The category generated a turnover of over 729 million euros and nearly 520 million packs sold. The average number of product lines per outlet (-0,3%) and promotional intensity by unit (-0,5%) both saw slight declines, with the latter standing at 12,5% (NIQ data, total Italy, Hypermarkets+Supermarkets+Traditional stores+Discount stores).
Performance by geographical area and distribution channel
The sector shows an almost uniform trend across the 4 Nielsen Areas. «All areas record value growth and declines in packs – comments Daniela Villano of NIQ –. Area 3 stands out, with value growth of 2,8%, despite a decline in packs (-0,5%). The average price per pack is rising in all areas, while promotional intensity is falling, particularly in Area 3 (-1% compared with the previous year), although it remains in line with the market average intensity (12,5%)». Looking at the channels, modern distribution accounts for more than 77% of the value of this sector. Supermarkets stand out, accounting for 44,5% of the entire market’s value (+0,2% compared with the previous year) and also holding the largest share by packs (41,1%; +0,3%), despite the 3,7% increase in the average price per pack (1,52 euros). Discount stores generate a value equal to 22,9%, slightly higher than that of hypermarkets (22,4%), but the latter are growing compared with the previous year (+0,3 points), unlike discount stores, which show a slight decline (-0,1 points). «The average price is rising in all channels and reaches 1,62 euros per pack in hypermarkets (+2,6%) – Daniela Villano continues –, while the percentage of packs sold on promotion remains stable only in hypermarkets and falls by 1,5% in discount stores. The average number of product lines per outlet is also declining, a trend seen across all channels except supermarkets (+0,3%)».
Segment performance
The flours and mixes segment is driven by soft wheat flours, which account for more than half of the value generated (62,1%). 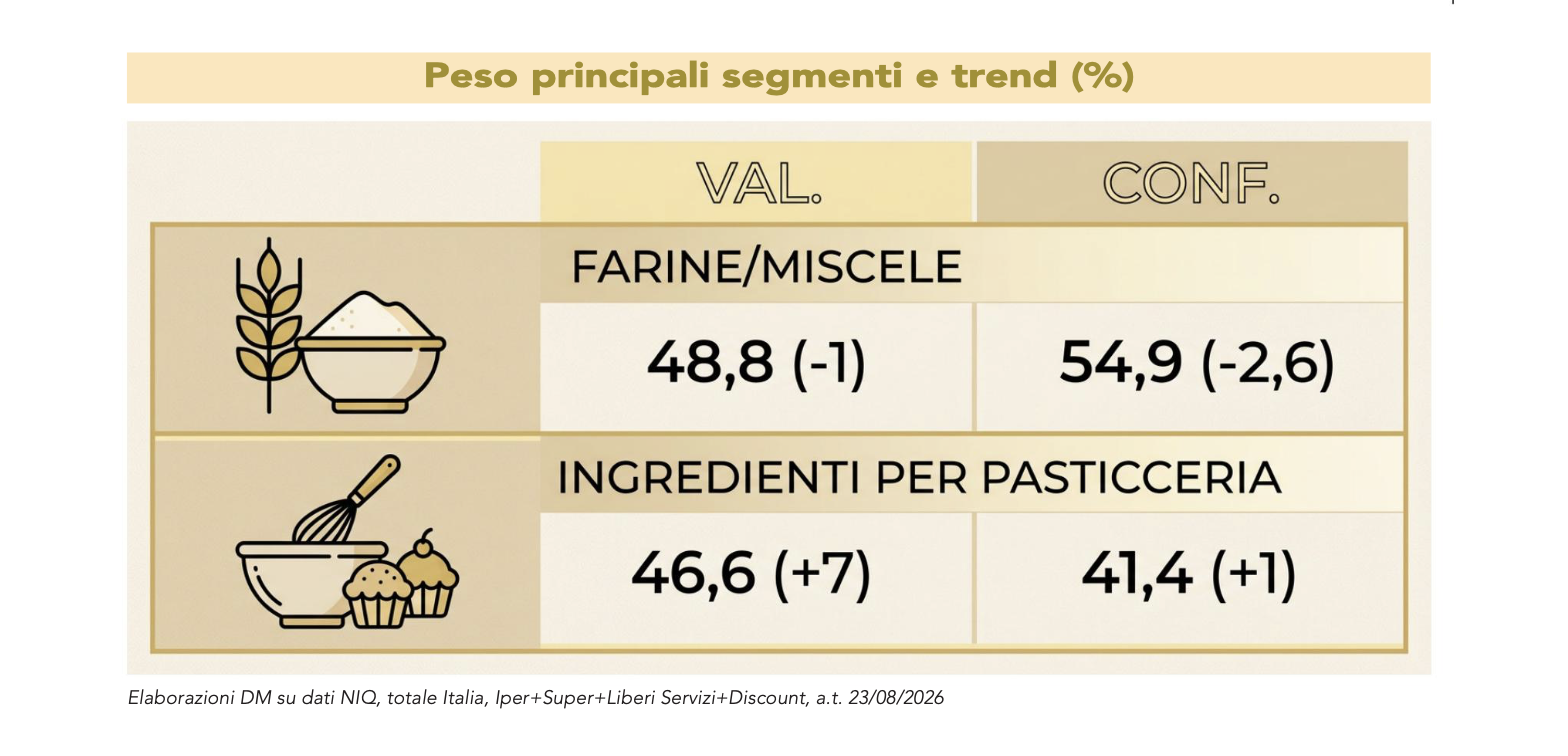 They are declining in value in all areas and channels, with the exception of slight growth in value (+0,7%) and packs (+0,5%) recorded in hypermarkets. For this segment, the average price per pack is rising in all areas and channels, except in Area 1 and in discount stores, where it remains fairly stable (-0,1%). Promotional packs are declining in all areas, particularly in Areas 1 and 3, with -2,3% and -2,6% respectively, and in all channels, especially discount stores (-4,5% pack Int. Idx). In addition, for soft wheat flours, the average number of product lines is increasing in modern distribution in Areas 1 and 3 and declining in discount stores (-2,2%). «As for baking ingredients – concludes the NIQ analyst –, the standout subsegments are flavouring baking ingredients and decoration baking ingredients. Together, these two segments account for 49,2% of the value generated by the category. Decoration ingredients stand out, growing in Area 2 (+8,6% in value and +1,9% in packs) and in discount stores (+10,7% in value and +5,6% in packs). In discount stores, growth is attributed to the rising average price per pack (1,74 euros; +4,9%), promotional intensity by pack (10,5%; +3,8%) and the average number of product lines per outlet (10,1; +1,5%)».
Read more in DM Magazine November 2026
This article was translated from the original version in Italian with the assistance of artificial intelligence. In case of discrepancies, please refer to the original version in Italian.